Madison Rodak

You are here:
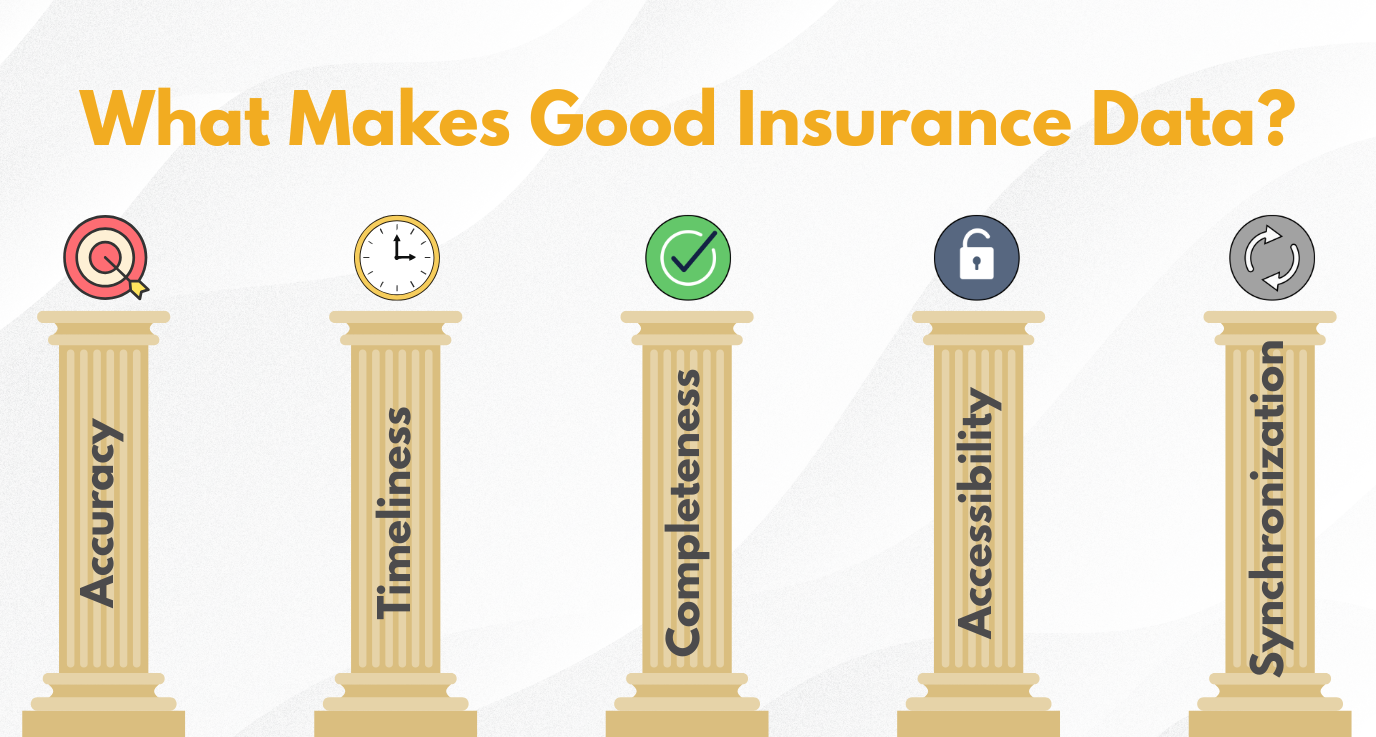
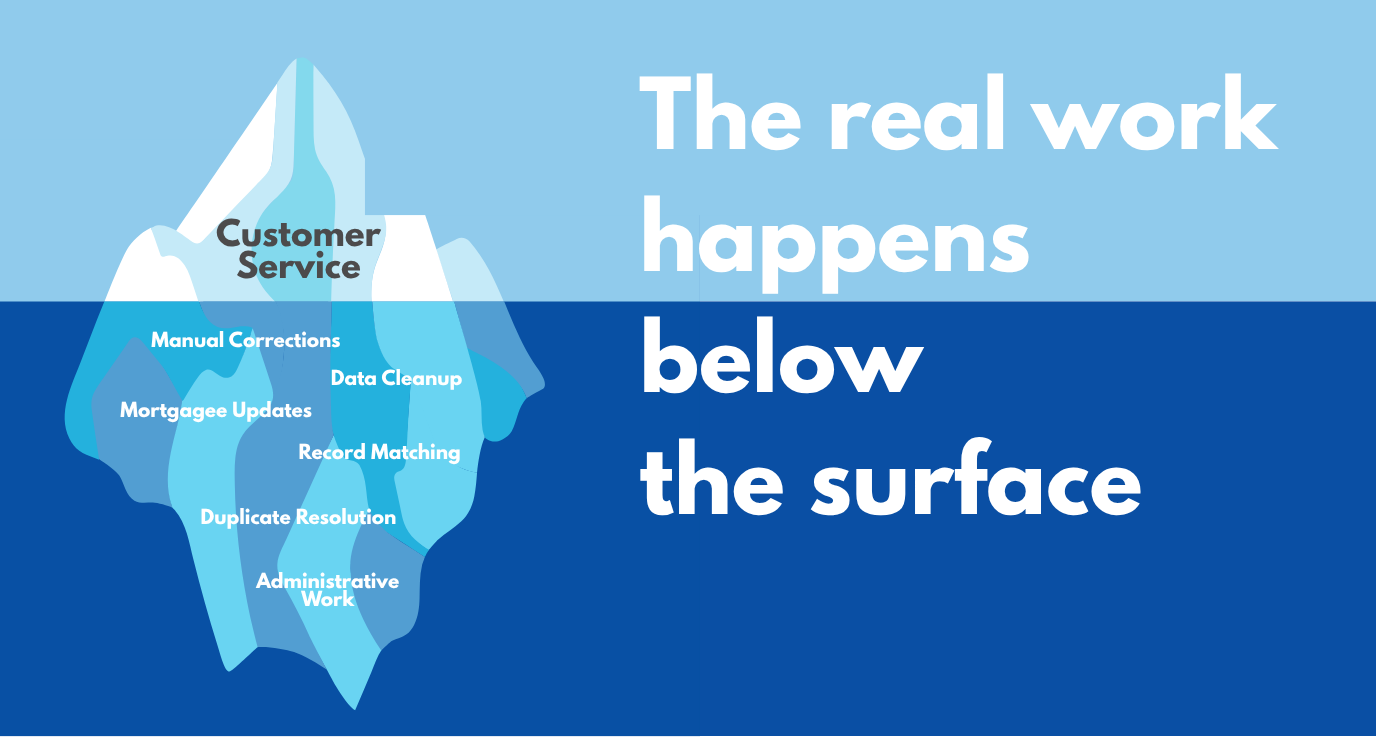
What Makes Good Insurance Data “Good”?

When we talk about data quality, accuracy is often the first thing people mention. It is also the easiest one to measure, which is probably why it gets the most attention. A policy number is either correct or it is not. An address either matches the property or it does not.

Read article
The Hidden Cost of “Just Checking on Insurance”: Why Lender Servicing Is Overdue for Automation

Ask any P&C insurance servicing team what eats up their day, and you'll hear the same answer: lenders and lienholders calling, emailing, and faxing to verify coverage, request notices, or correct mortgagee information. One major carrier fields over a million of these Financial Institution Inquiries every single year. That's not a service team -- that's a call center dedicated entirely to answering questions that the right technology could answer instantly.

Read article
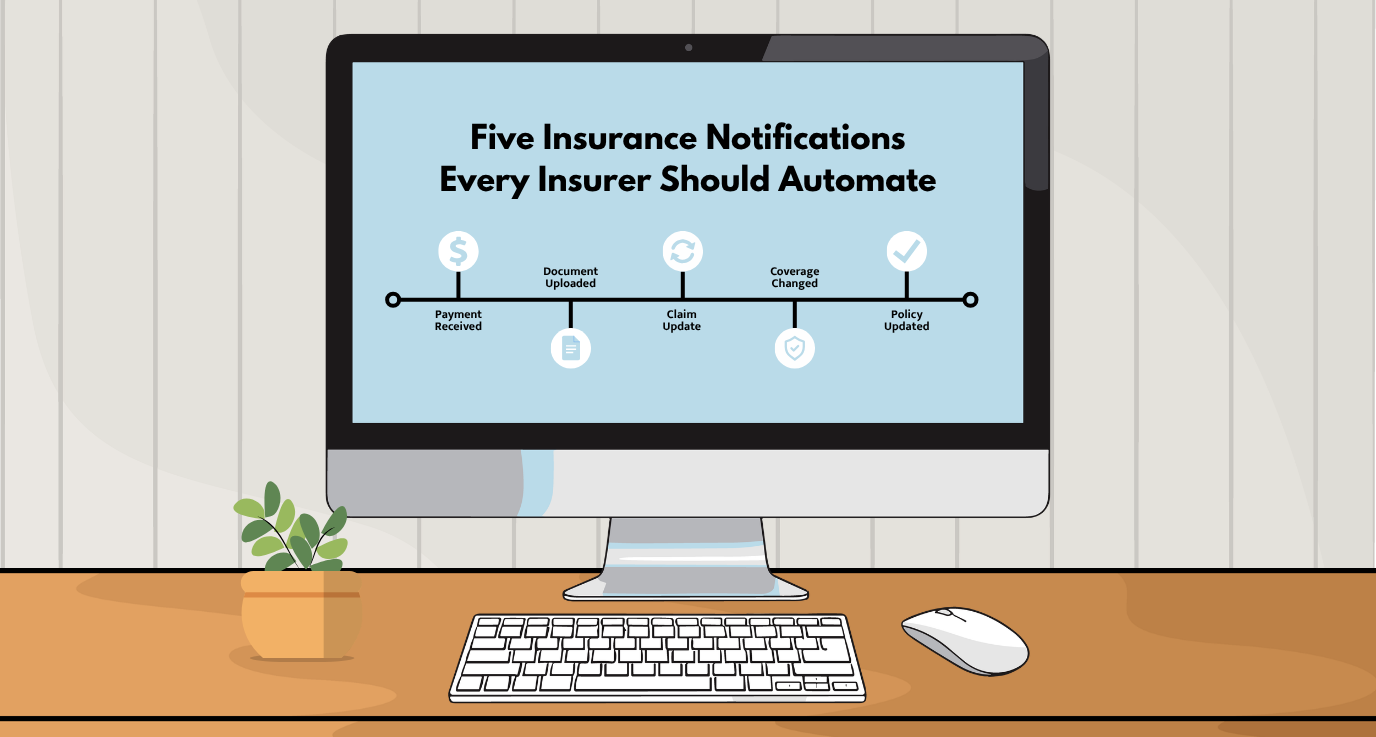
Five Insurance Notifications Every Insurer Should Automate

The insurance industry has spent years automating underwriting, pricing, fraud detection, and claims. Communication, oddly enough, still feels like an afterthought. Customers often learn something important only after they decide to log in, call customer service, or receive a letter days later.

Read article
Wearables and the Quiet Expansion of Life Insurance Underwriting

Life insurance underwriting has, for a long time, been a single, heavily scrutinized moment. A medical exam, a blood panel, a questionnaire about family history and lifestyle, and from that snapshot, an insurer builds a risk classification that follows the policy for years, sometimes decades. The model assumes that a person's risk profile, once assessed, stays reasonably stable, or at least stable enough that re-underwriting every year would not be worth the cost.

Read article