Welcome to LenderDock
Learn more about the legs on the stool; The LenderDock Eco-System.
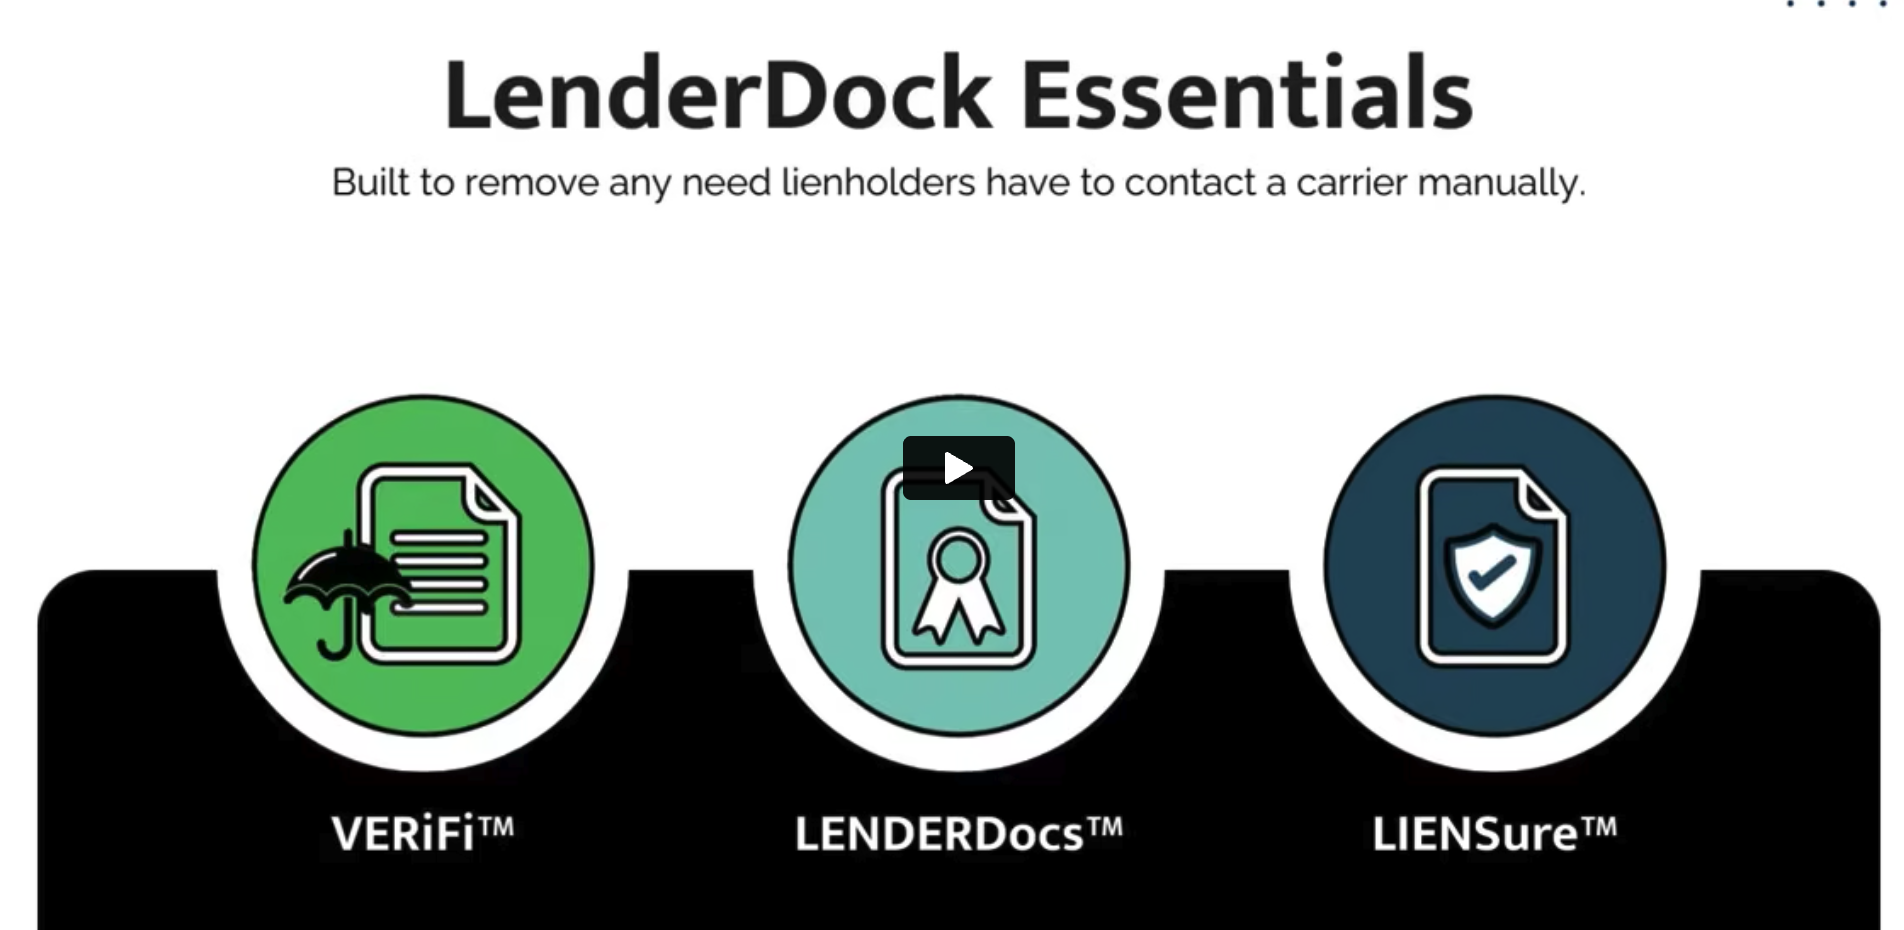
LenderDock provides real-time, insurance policy details through its magical web portal or its APIs.
LIENSure sends corrections digitally, straight from the financial source of truth and in bulk for easy processing.
ESCROWPay verifies what’s actually due before the money moves, then sends the payment and reconciliation data digitally.
NOTiFi delivers required policy, coverage, and billing notices in the formats lienholders actually use
At least check out the genesis of LenderDock Video. It’ll all make sense, the eco-system, that is.
Learn more about our great leadership team and our amazing, people-first, company culture.
There’s a lot going on at LenderDock and in our industries. We threw it all here to make it easier to keep up.
We go to a lot of events and we love to eat. See our calendar of where we’ll be.
New webinars will be coming quite frequently. Educational, success, and sales.
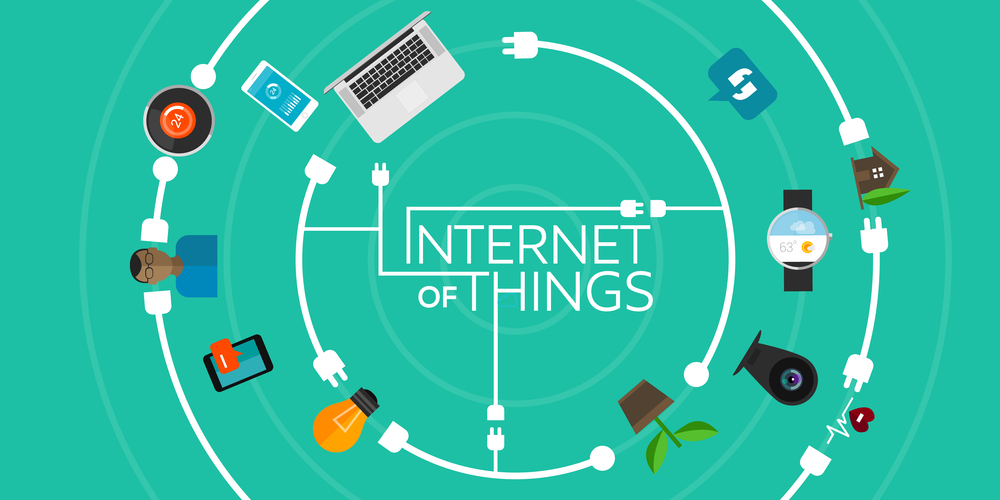
The internet has changed how we live, work, and connect with others. Now, with the proliferation of connected devices, we are entering a new era—the Internet of Things (IoT).
The Internet of Things encompasses a vast array of interconnected devices imbued with sensors and sophisticated software, empowering them to seamlessly gather, analyze, and exchange data.
This intricate web of connectivity enables devices to communicate with each other creating a dynamic ecosystem where information flows freely among various endpoints.
The integration of the Internet of Things in the insurance sector brings forth a plethora of advantages. From efficient customer service to simplified claims processing, IoT not only prevents risks and losses but also significantly reduces operational costs.
By utilizing data from internet-connected devices, IoT-connected insurance refines the understanding of risks. For instance, in auto insurance, risk assessment is usually done using historical data and actuarial statistics to establish a customer’s risk profile, ultimately determining the premium.
Now, with IoT devices like vehicle sensors and smartphone apps, real-time data can be collected, recorded, and processed leading to more accurate premiums.
Telematics, a prime example of IoT implementation in auto insurance, utilizes sensors installed in vehicles to collect real-time data on driving behavior. This data enables insurers to personalize premiums based on individual driving habits, promoting safer driving practices and reducing the risk of accidents.
Using Snapshot, a telematics program by Progressive, the insurer gathers real-time data to understand the driving habits of its policyholders. Premium discounts are given to drivers who drive safely.
In property insurance, smart home devices such as security cameras, motion sensors, and leak detectors have revolutionized risk mitigation. By continuously monitoring homes for potential hazards, these devices help prevent damages, minimize losses, and enable insurers to offer tailored coverage to homeowners.
Since 2015, American Family has partnered with Ring Video Doorbell to offer homeowner’s insurance. If you install the latter’s doorbell equipped with a Wi-Fi-enabled camera as part of your homeowner’s coverage, the company will reimburse your deductibles in case of burglary.
Health insurance has embraced wearables like fitness trackers and smartwatches to promote wellness and reduce healthcare costs. These devices monitor users’ vital signs, activity levels, and overall health, allowing insurers to incentivize healthy behaviors and provide personalized coverage plans.
As an example, John Hancock Life Insurance Co. includes a Wellness Incentive Benefit Endorsement. With it, policyholders can benefit from premium savings, Amazon gift cards, travel discounts, and more by engaging in health and wellness activities like regular exercise while using an approved fitness-tracking device.
Drones equipped with high-resolution cameras and sensors conduct aerial surveys of agricultural fields, capturing detailed imagery of crop health, moisture levels, and pest infestations. Insurers analyze this data for accurate risk assessment, identifying potential hazards like drought or flooding.
Today, drones and specialized software like Pix4Dfields are used to assess crop damage in agricultural policies backed by the Risk Management Agency under the U.S. Department of Agriculture.
In addition, loss adjusters can swiftly assess affected assets and survey hard-to-reach places using drones, reducing claims costs by up to 30 percent, as reported by Forbes. As a result, claims are expedited and costs are reduced, leading to increased customer satisfaction and profits, respectively.
Despite the remarkable advancements, the integration of IoT in insurance comes with its own set of challenges. From data privacy and security concerns to the need for standardization and interoperability, insurers must navigate this complex maze of unfamiliarity to achieve gains brought by the Internet of Things.
Great video on the inception of LenderDock and how it came to pass.
CEO Frank Eubank explores the influence of AI on the insurance sector alongside special guest Benjamin Bomhoff from Fleming Insurance Holdings.
The internet has changed how we live, work, and connect with others. Now, with the proliferation of connected devices, we are entering a new era—the Internet of Things (IoT).
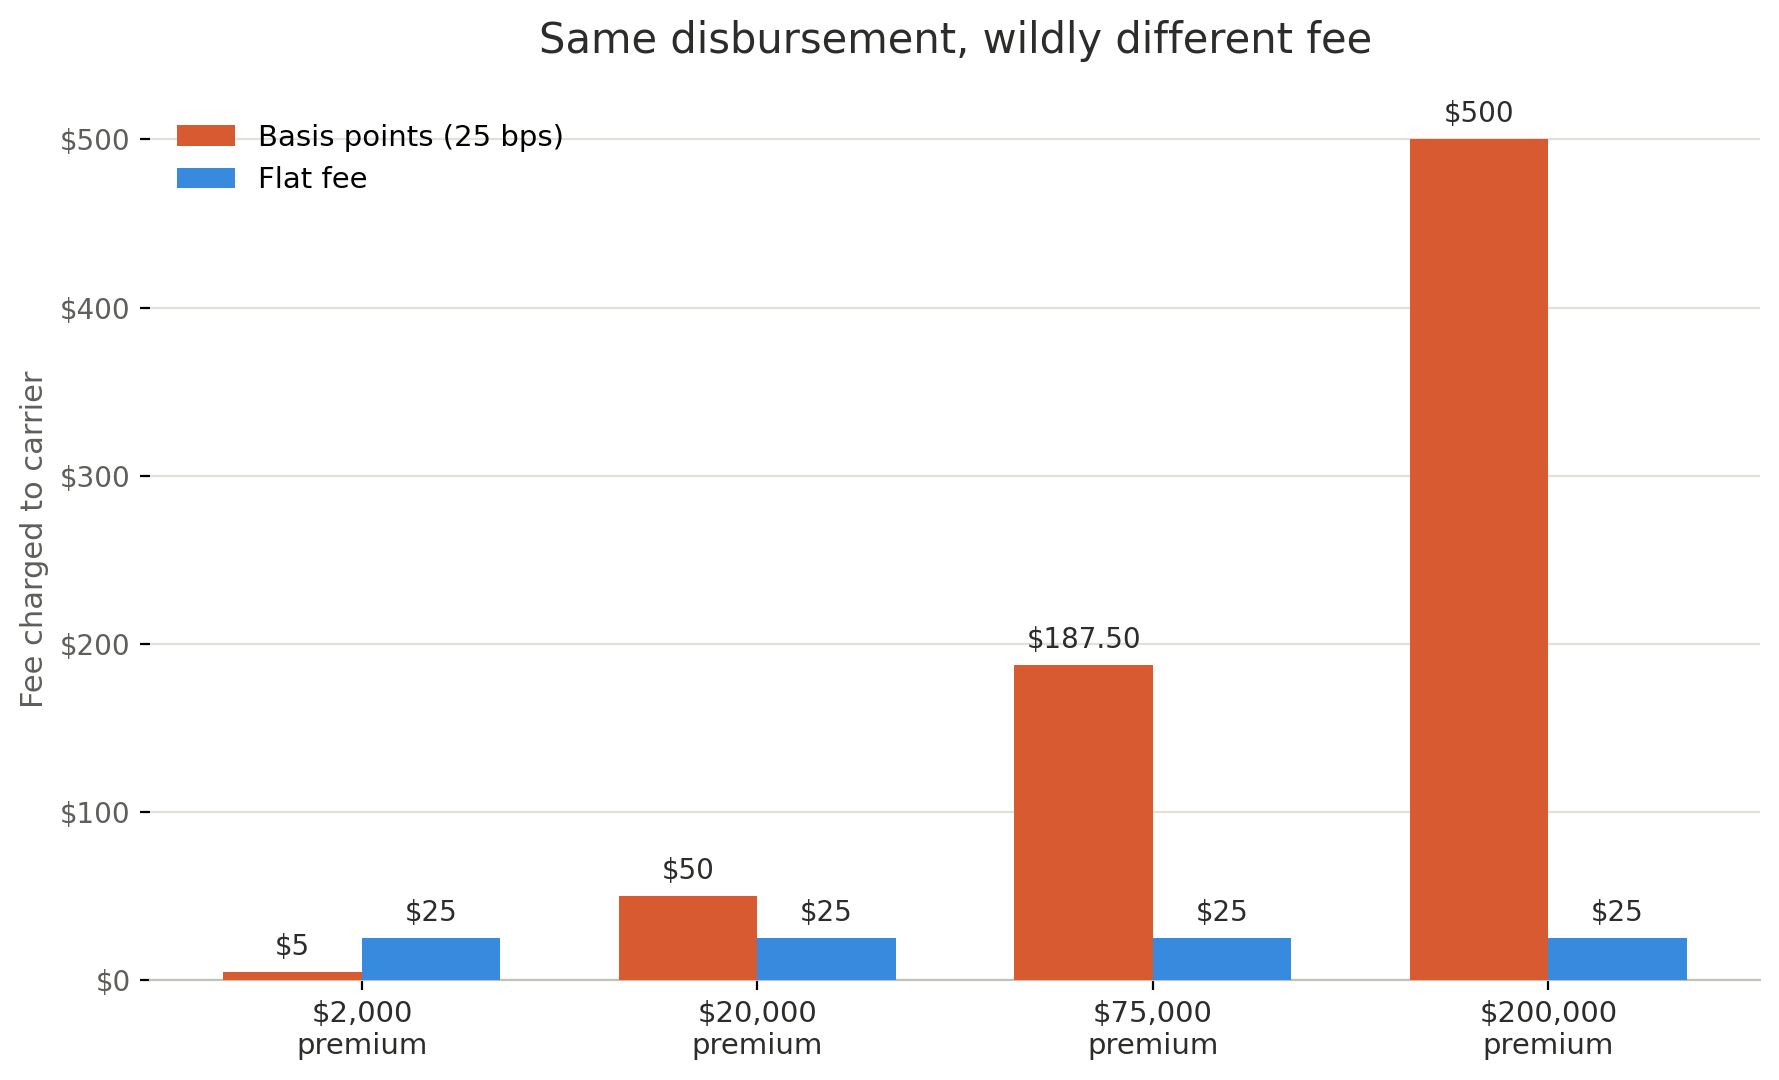
There’s a moment in almost every client relationship where the pricing model quietly reveals whose side you’re on. Basis points are one of those moments — and they reveal a lot.
RPA is the use of low-code software bots to automate repetitive and rule-based tasks within business processes.
We consectetur adipiscing elit tempor incididunt ut labore. Wondering ipsum dolor sit amet? We consectetur adipiscing ipsum nulla glavrida elit tempor incididunt.