From Policy Change to Action: Why Timing Matters in Insurance
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
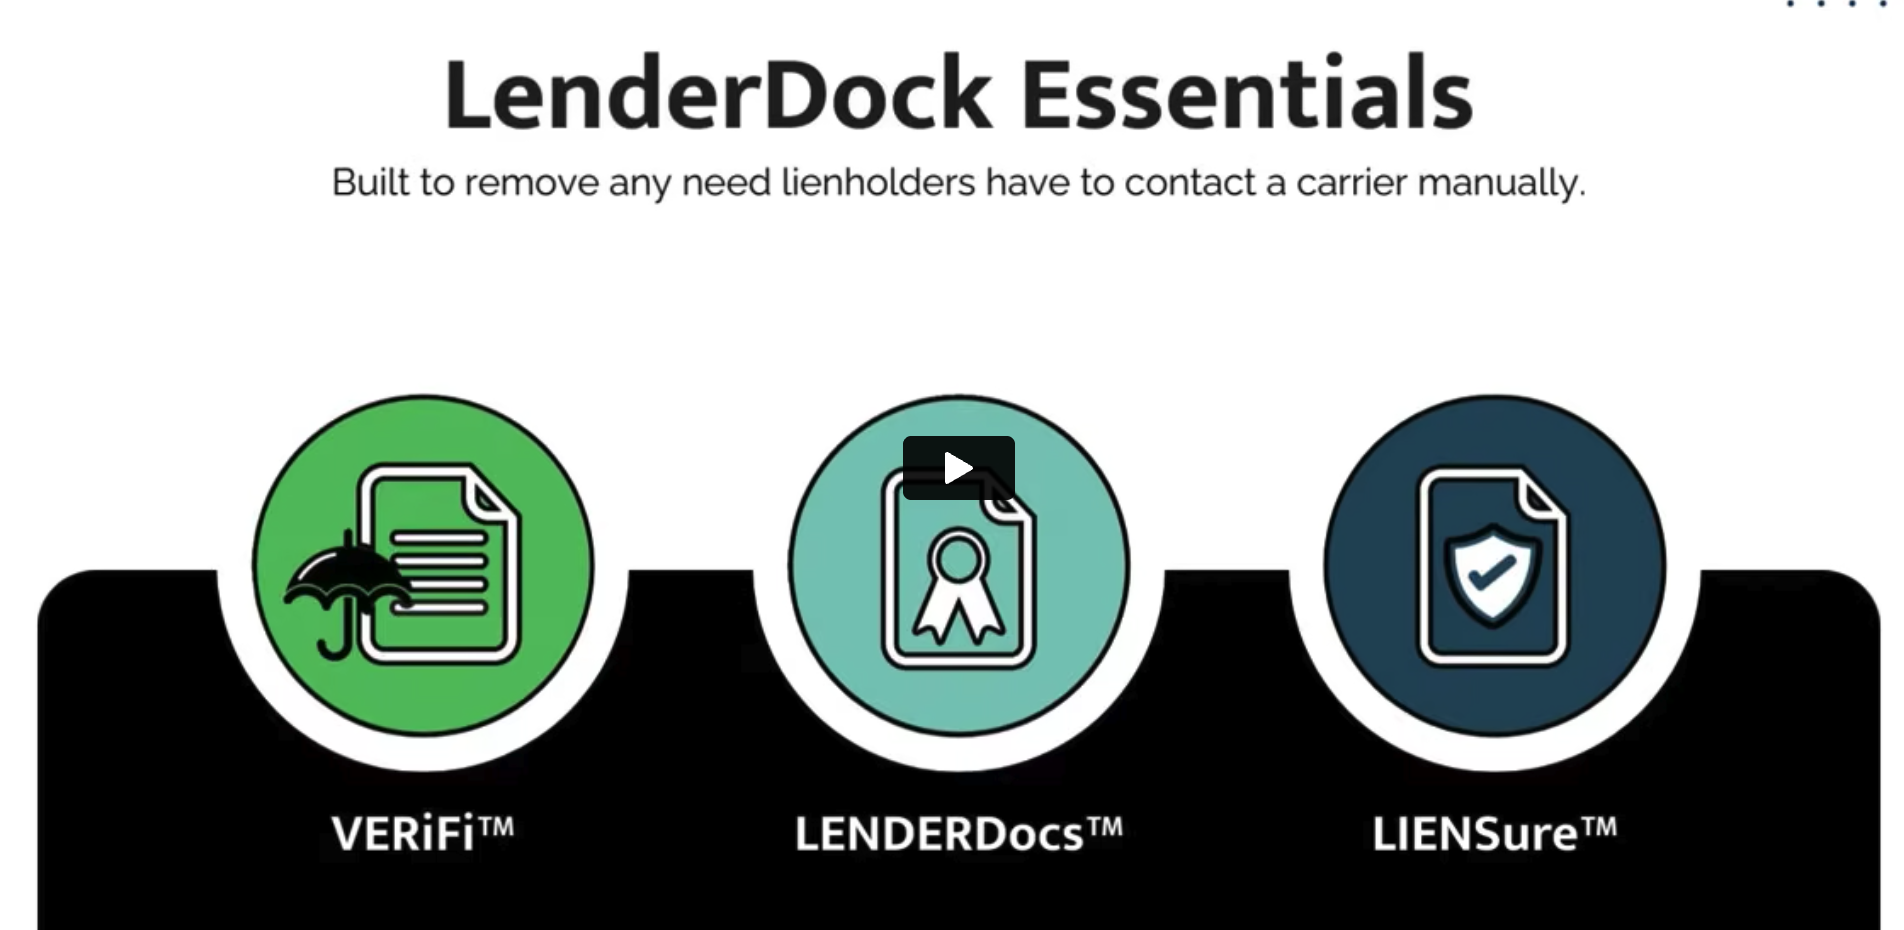
LenderDock provides real-time, insurance policy details through its magical web portal or its APIs.
LIENSure sends corrections digitally, straight from the financial source of truth and in bulk for easy processing.
ESCROWPay verifies what’s actually due before the money moves, then sends the payment and reconciliation data digitally.
NOTiFi delivers required policy, coverage, and billing notices in the formats lienholders actually use
At least check out the genesis of LenderDock Video. It’ll all make sense, the eco-system, that is.
Learn more about our great leadership team and our amazing, people-first, company culture.
There’s a lot going on at LenderDock and in our industries. We threw it all here to make it easier to keep up.
We go to a lot of events and we love to eat. See our calendar of where we’ll be.
New webinars will be coming quite frequently. Educational, success, and sales.
One of the most transformative impacts of insurtech is in the realm of microinsurance.
Insurtech plays a pivotal role in making insurance accessible and affordable to low-income populations and underserved markets.
According to the WHO, in 2021, about 4.5 billion people lacked full coverage for essential health services. Among them, 344 million were sinking deeper into extreme poverty due to unaffordability of such basic and important needs.
Microinsurance is designed to provide financial protection to individuals with low incomes often excluded from traditional insurance markets. It covers a range of risks, including health, life, agriculture, and property, offering smaller coverage amounts.
This also comes with the benefit of lower premiums that low-income households can afford.
The challenge with microinsurance has traditionally been its sustainability and reach, given the high administrative costs and the difficulty in reaching dispersed, low-income populations.
This is where insurtech comes in.
As we have seen in previous articles, insurtech—a term that combines “insurance” and “technology”—is revolutionizing traditional insurance practices by leveraging digital technologies to enhance efficiency, reduce costs, and improve customer experiences.
This can be seen in:
Mobile phones are ubiquitous even in low-income communities, making them an ideal medium for distributing microinsurance products.
Microinsurance providers use MNOs – mobile network operators – for policy issuance, premium collection, and claims processing, significantly reducing operational costs and making microinsurance viable in both the short and long term.
Unlike conventional insurance, which usually sets high margins, microinsurance sustains itself with smaller margins but with a very large pool.
Blockchain can enhance transparency and trust in microinsurance by providing a secure and immutable ledger of transactions. This is particularly useful in preventing fraud and ensuring that claims are processed swiftly and accurately.
AI and machine learning algorithms can analyze vast amounts of data to assess risk more accurately and personalize insurance products. Such technologies can help design affordable insurance products tailored to the specific needs of low-income customers.
IoT devices can provide real-time data that helps in better risk assessment and management. For example, in agricultural microinsurance, IoT sensors can monitor weather conditions and crop health, enabling more precise insurance coverage and quicker claim settlements.
Drones are emerging as valuable tools in the microinsurance sector, especially in agriculture.
They can monitor crop health and growth conditions, offering detailed insights that improve risk assessment. Specifically, they can reach hard-to-access areas for monitoring and assessment by insurers, thereby minimizing administrative costs and saving time.
Several U.S. insurance companies are at the forefront of deploying insurtech solutions for microinsurance:
Lemonade
While primarily known for renters and homeowners’ insurance, Lemonade’s AI-driven platform is a model for how technology can streamline insurance processes.
Their approach of using AI for policy management and claims processing can be adapted to microinsurance markets. For instance, Lemonade uses AI to assess claims based on photos of goods.
By minimizing administrative costs, micro insurers can offset operational expenses, thereby reducing premium rates in the long run.
Allianz
Through its subsidiary Allianz X, the company invests in insurtech startups focusing on underserved markets.
They have supported ventures like BIMA, which uses mobile technology to offer affordable microinsurance products in developing countries. The latter’s insurance products range from life and health insurance to personal accident coverage.
Ric Micro Parametric
Ric is actively transforming the U.S. parametric catastrophe insurance market through a strong commitment to innovation.
By utilizing parametric insurance models, Ric provides quick and efficient payouts based on predefined parameters like rainfall levels during major flooding events.
Insurtech is playing a crucial role in expanding the reach and efficiency of microinsurance.
By harnessing mobile technology, blockchain, AI, and others, insurtech companies are overcoming traditional barriers and making insurance accessible to those most marginalized.
As these technologies continue to evolve, they promise to bring even greater innovations to the microinsurance sector, fostering financial inclusion and resilience among low-income populations.
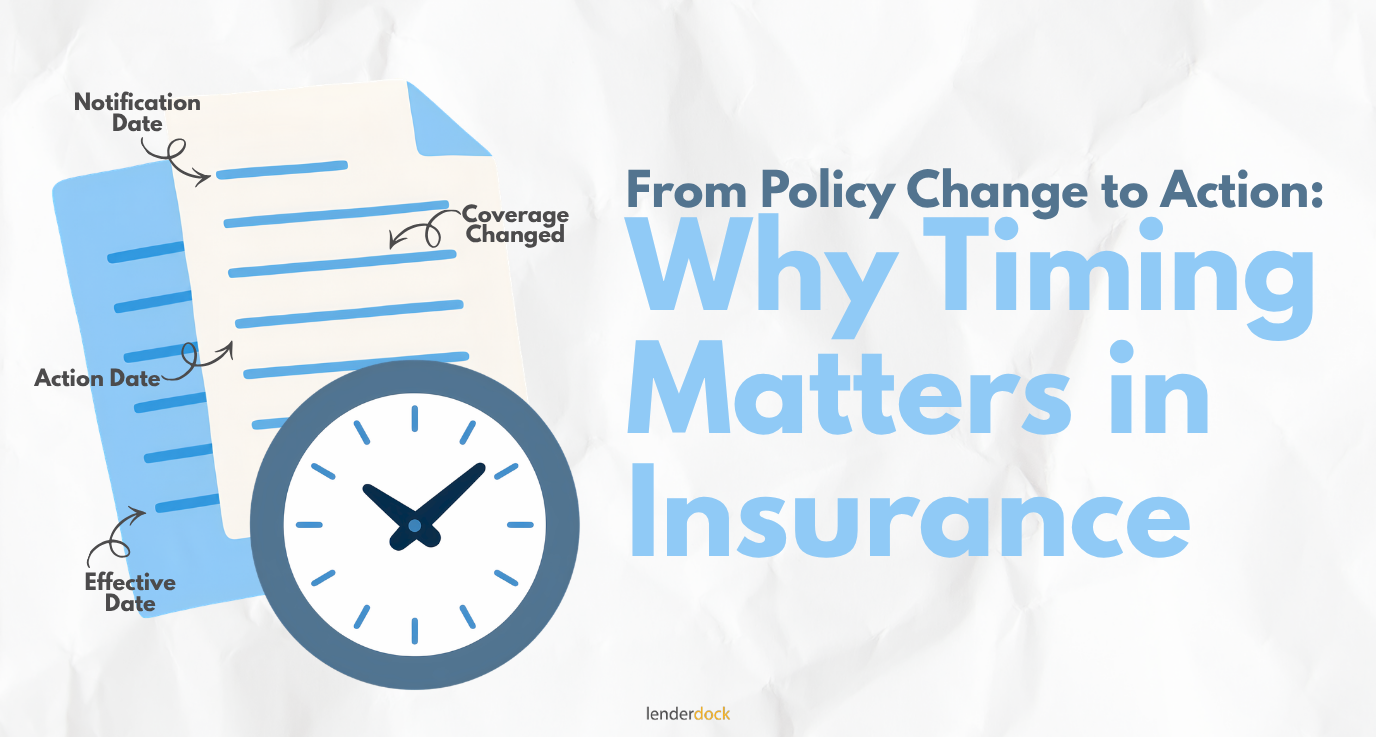
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
A two-day lag between a policy change and everyone finding out about it used to be annoying, not dangerous. Someone made a call, waited, got an answer, and moved on with their day.
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
Insurance verification is a routine part of the lending and insurance process. A lender needs to know whether a policy is active. A mortgage servicer may need to confirm coverage or mortgagee information. An insurance…
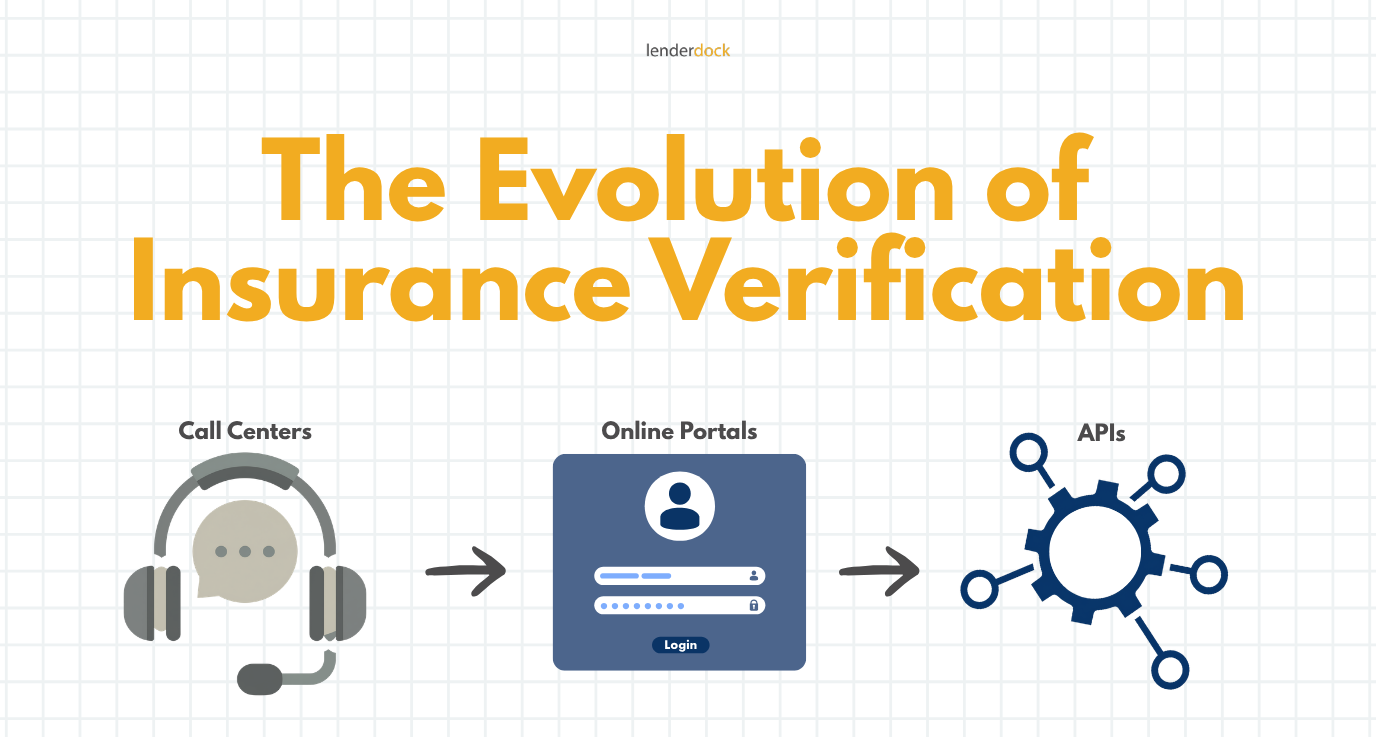
In the earliest version of insurance verification, the person answering the phone actually had to know things. They pulled a physical file, checked handwriting against a ledger, and made a judgment call about whether what…
Two insurers can each have perfectly accurate, well-maintained policy databases and still fail to exchange a single piece of usable data between them.
Every single day, insurance workers face a mountain of simple questions. Are they tired of answering the same questions about policy coverage all day long? Yes, they are. When banks or lenders need to check…
A title company closing a home sale needs to confirm the seller’s policy is active before the deal can move. An auto lender needs the same thing before releasing funds on a car loan. A…
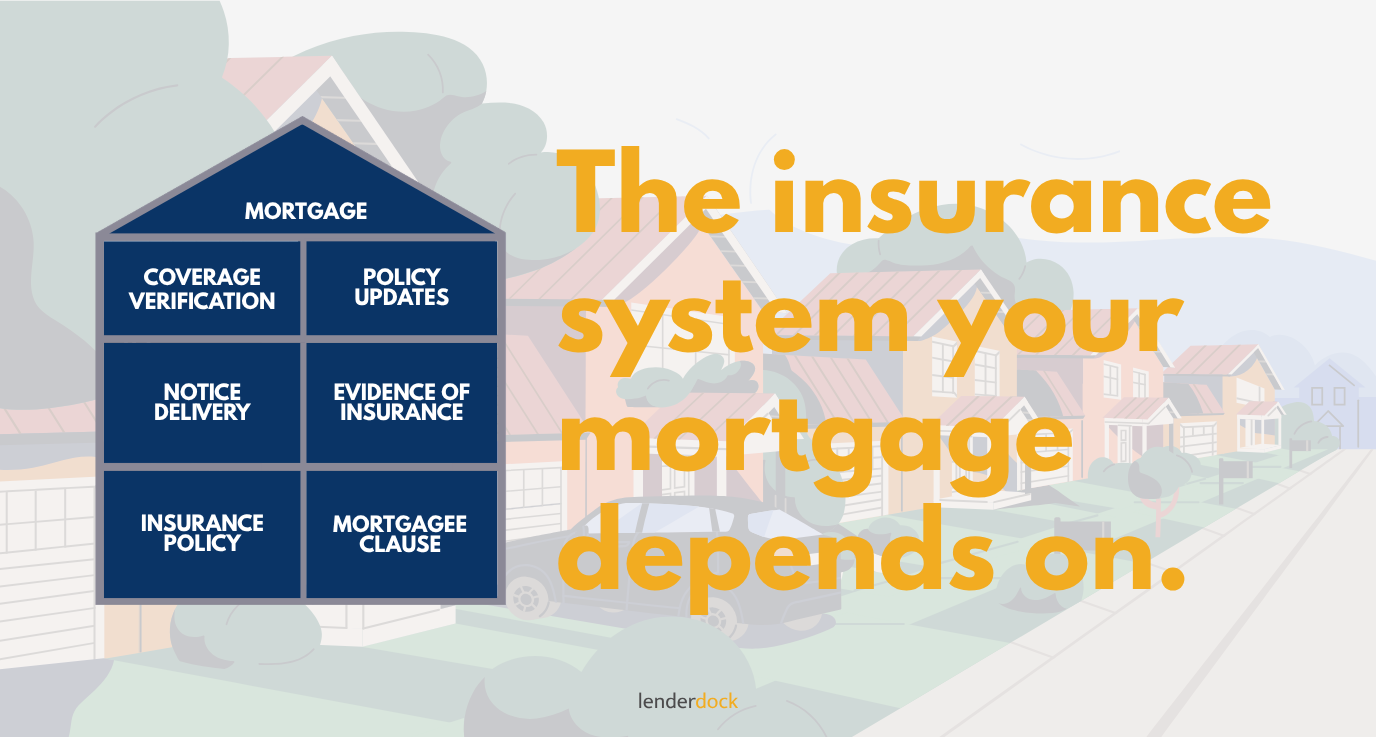
Most people who take out a mortgage never think about insurance as part of the loan itself. It feels adjacent, a separate purchase, something the lender requires but does not really participate in beyond checking…
Mortgagee corrections are a routine part of insurance servicing, but the process behind them is often anything but simple. A lender may find that the mortgagee’s name or address on a policy is out of…
We consectetur adipiscing elit tempor incididunt ut labore. Wondering ipsum dolor sit amet? We consectetur adipiscing ipsum nulla glavrida elit tempor incididunt.