From Policy Change to Action: Why Timing Matters in Insurance
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
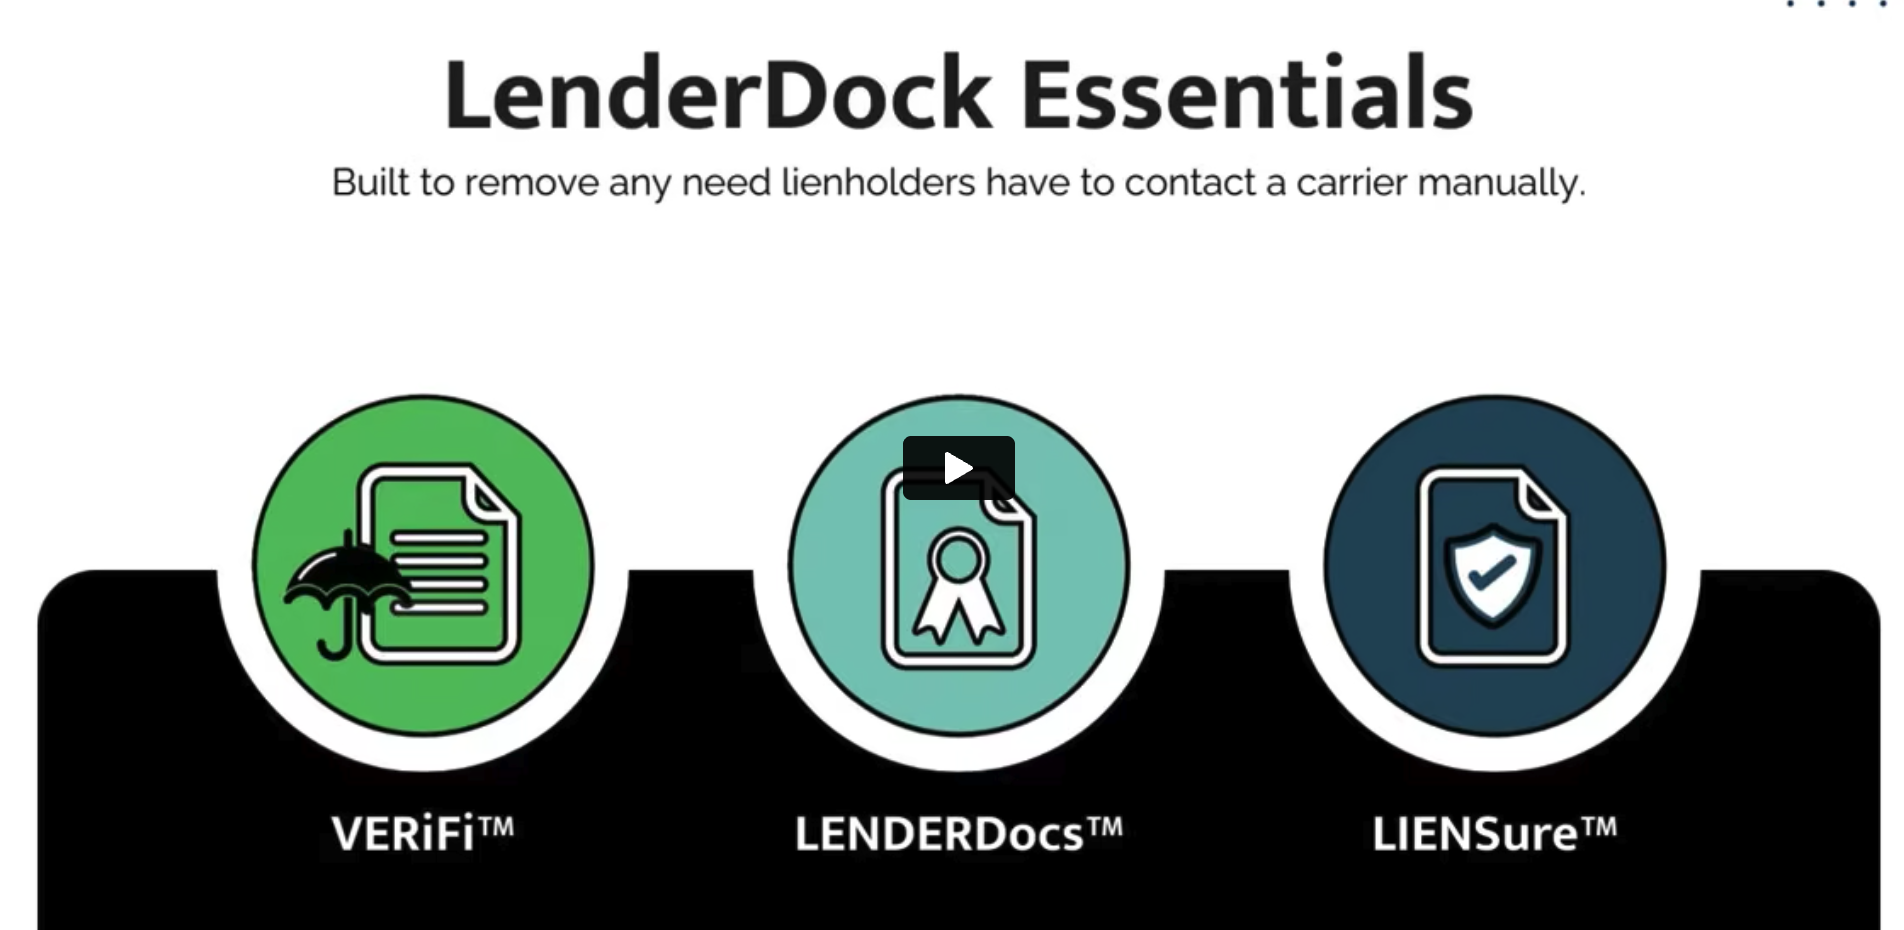
LenderDock provides real-time, insurance policy details through its magical web portal or its APIs.
LIENSure sends corrections digitally, straight from the financial source of truth and in bulk for easy processing.
ESCROWPay verifies what’s actually due before the money moves, then sends the payment and reconciliation data digitally.
NOTiFi delivers required policy, coverage, and billing notices in the formats lienholders actually use
At least check out the genesis of LenderDock Video. It’ll all make sense, the eco-system, that is.
Learn more about our great leadership team and our amazing, people-first, company culture.
There’s a lot going on at LenderDock and in our industries. We threw it all here to make it easier to keep up.
We go to a lot of events and we love to eat. See our calendar of where we’ll be.
New webinars will be coming quite frequently. Educational, success, and sales.
Though the concept of being “customer-centric” isn’t necessarily wrong, it is important to realize that a balance must be struck for such an idea to be successful. Have we gone so far in this direction as to make its effectiveness diminish?
On-demand insurance has quickly become the go-to choice for entrepreneurs and gig economy workers alike – and it’s no wonder why. Insurtech companies have been thrilled at its surge in popularity, as more people are leaning towards a familiar user experience with their insurance purchase that mimics shopping on Amazon or another online platform. This shift toward relying heavily on smartphones, applications, or other advancements is transforming how we shop for coverage today.
Subsequently, the marriage between technology and insurance resulted in the origination of on-demand insurance. Now, customers can shop for and purchase policies with no need to seek assistance from an insurance broker, or agent. For instance, a new founder can acquire a general liability policy or even errors and omissions coverage rapidly with just a few taps on their smartphone.
As commercial insurance brokers look to the future, they are taking advantage of on-demand technologies like mobile apps that make it easier for them to connect with their clients. From submitting vital documents, making payments, and even inviting collaborators onto policies — there is no denying that this industry has undergone a modern transformation at an astonishing rate. Even though some may see insurance as archaic in nature, technology continues to prove itself as the driving force behind its innovation.
Unveiling the Impact of AI and Machine Learning on Insurance
Before we delve into the exciting changes that have taken place in the industry due to embracing these progressive technologies, it’s important to note how underwriting has been a major part of this transformation. It is widely accepted now that Artificial Intelligence (AI) and Machine Learning are changing the way insurance companies operate – from “detect and repair” to “predict and prevent”. This deserves closer attention as it could lead us toward an even more advanced future for insurers.
In the past, traditional underwriting processes were quite laborious and slow due to the manual evaluation of threats by human personnel. Fast forward to today, where automated underwriting is enabled by advanced algorithmic technology allowing businesses to make more precise decisions in a matter of moments! This revolutionary process has revolutionized risk management for modern-day organizations looking for ways to thrive in our dynamic digital world.
Despite our present-day trials, we should recall the not-so-distant past and its importance:
Insurance may be too easily accessible, especially with the influx of insurtechs that offer automated underwriting. These efficient tools can become a double-edged sword when it comes to larger companies or riskier industries like crypto and fintech– while they are great for simpler risks and smaller businesses, more intricate profiles require expert oversight in order to effectively secure coverage.
The Threats of On-Demand: Unnoticed and Underestimated
On-demand insurance has revolutionized the lives of many, and few would voice opposition to its benefits. Yet, when it comes to introducing new technologies, we must remain mindful that these advancements come with their own set of potential risks.
Let’s explore the double-sided risks associated with adequate coverage. To begin, tech-dependent brokers frequently fail to advise customers properly on what insurance products they should apply for. Additionally, these brokers leave clients wondering how precisely their protection should be structured or classified in relation to their business model.
We’ve witnessed the unfortunate trend of consumers making crucial insurance decisions without consulting their broker, leaving them with huge coverage gaps and often denied claims. As you can imagine, this is an incredibly dangerous avenue to pursue. Thankfully, clients are now empowered to modify vital coverages such as limits and deductibles — which must be managed by someone knowledgeable about insurance for a successful outcome.
Moreover, automated underwriting can create scalability issues for the larger risks that bypass the system. Once a human underwriter evaluates them, they are likely to non-renew or increase rates sharply in order to match the actual risk.
Proven and Practical On-Demand Insurance Solutions
Insurance customers demand various forms of communication from their brokers, transforming the role of a commercial insurance broker to meet these needs. Some prefer personalized attention while others would rather tackle tasks using an app. To ensure customer satisfaction and provide prompt responses, many carriers have embraced automation technology for certain underwriting data that are quantitative. Moreover, clients expect swift reactions from their insurers – making this shift towards digitalization paramount in meeting consumer expectations.
We should anticipate consistent advancement of automated underwriting among traditional companies and insurtech organizations. Virtually all life insurance firms have previously utilized digital processes, while commercial lines are projected to become increasingly reliant on automated underwriting with the notion of “predicting and preventing” in mind.
Ultimately, automated or on-demand insurance solutions have their place in the industry. Yet we should understand when clients, brokers, and underwriters require specialist expertise and attention. Combining human experience with technology is achievable – only if both forces acknowledge each other’s strengths and limitations for what they are.
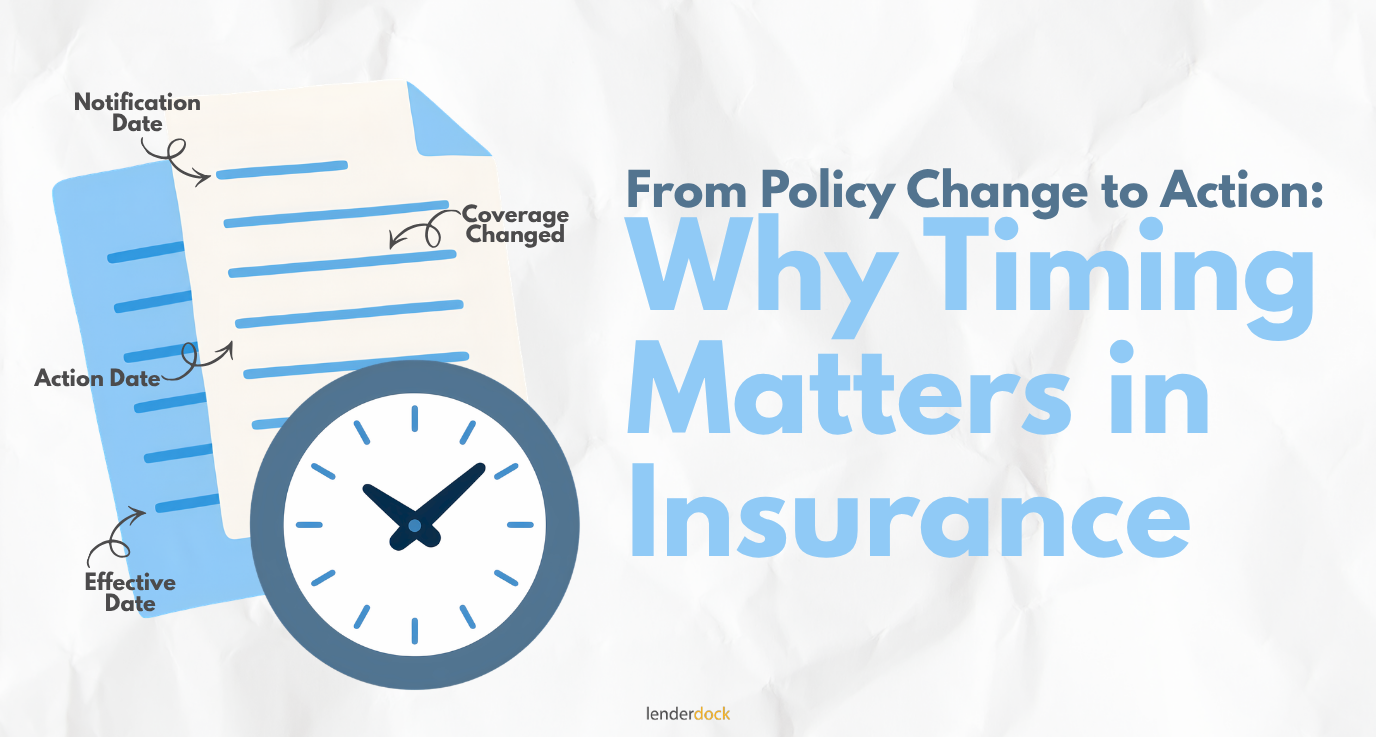
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
A two-day lag between a policy change and everyone finding out about it used to be annoying, not dangerous. Someone made a call, waited, got an answer, and moved on with their day.
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
Insurance verification is a routine part of the lending and insurance process. A lender needs to know whether a policy is active. A mortgage servicer may need to confirm coverage or mortgagee information. An insurance…
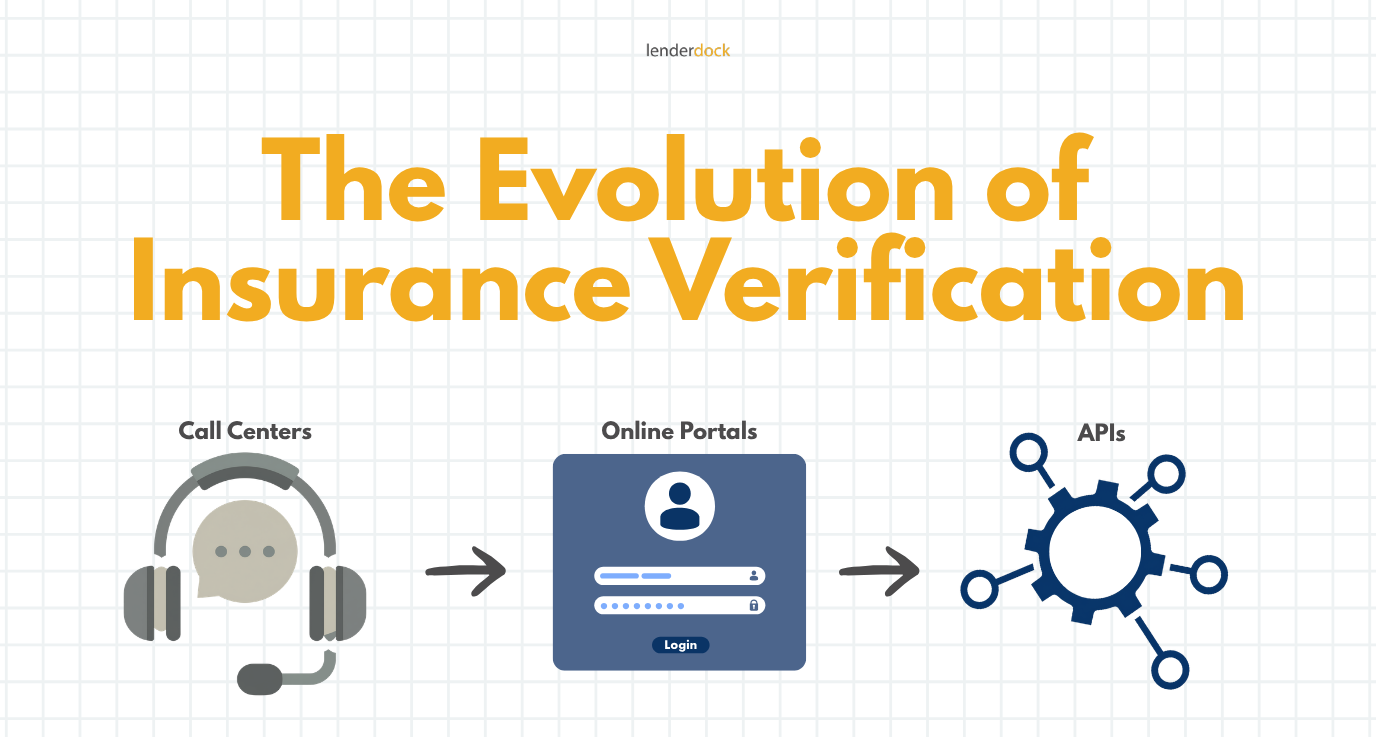
In the earliest version of insurance verification, the person answering the phone actually had to know things. They pulled a physical file, checked handwriting against a ledger, and made a judgment call about whether what…
Two insurers can each have perfectly accurate, well-maintained policy databases and still fail to exchange a single piece of usable data between them.
Every single day, insurance workers face a mountain of simple questions. Are they tired of answering the same questions about policy coverage all day long? Yes, they are. When banks or lenders need to check…
A title company closing a home sale needs to confirm the seller’s policy is active before the deal can move. An auto lender needs the same thing before releasing funds on a car loan. A…
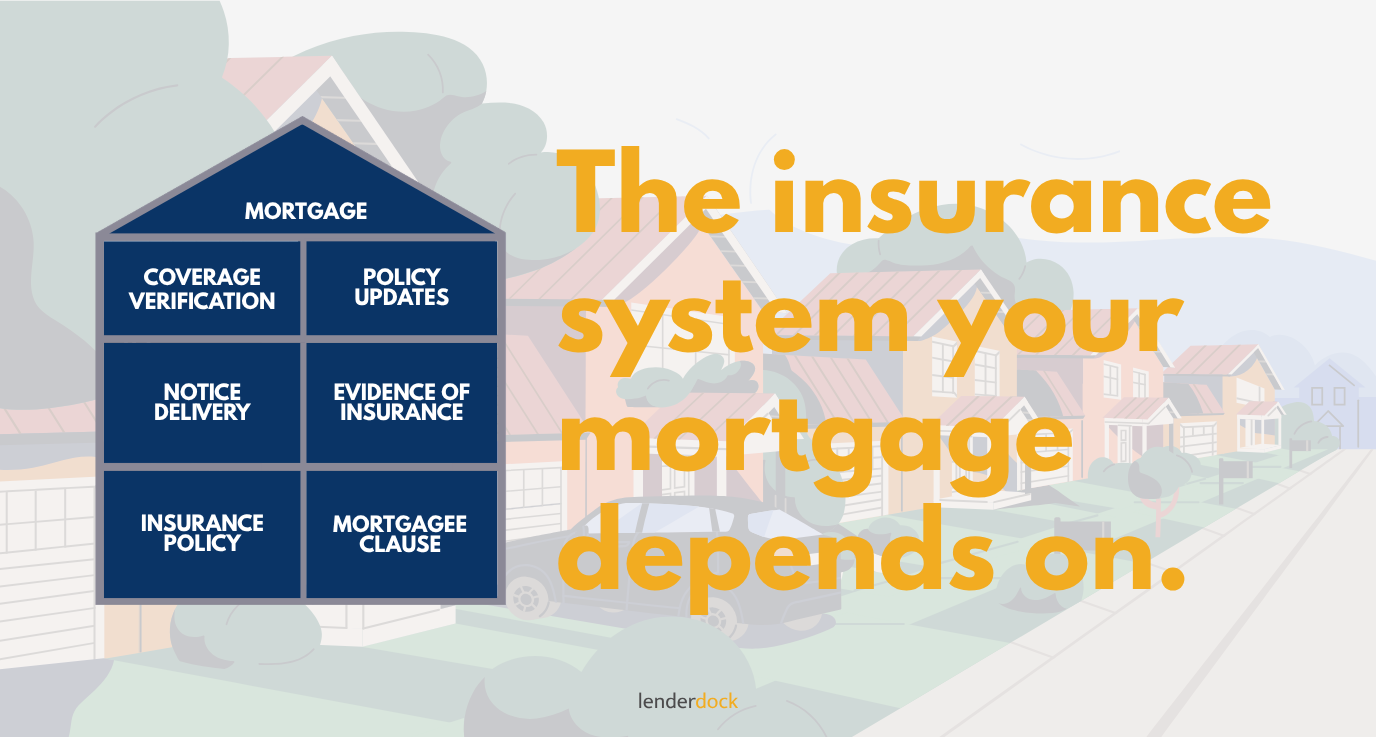
Most people who take out a mortgage never think about insurance as part of the loan itself. It feels adjacent, a separate purchase, something the lender requires but does not really participate in beyond checking…
Mortgagee corrections are a routine part of insurance servicing, but the process behind them is often anything but simple. A lender may find that the mortgagee’s name or address on a policy is out of…
We consectetur adipiscing elit tempor incididunt ut labore. Wondering ipsum dolor sit amet? We consectetur adipiscing ipsum nulla glavrida elit tempor incididunt.