From Policy Change to Action: Why Timing Matters in Insurance
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
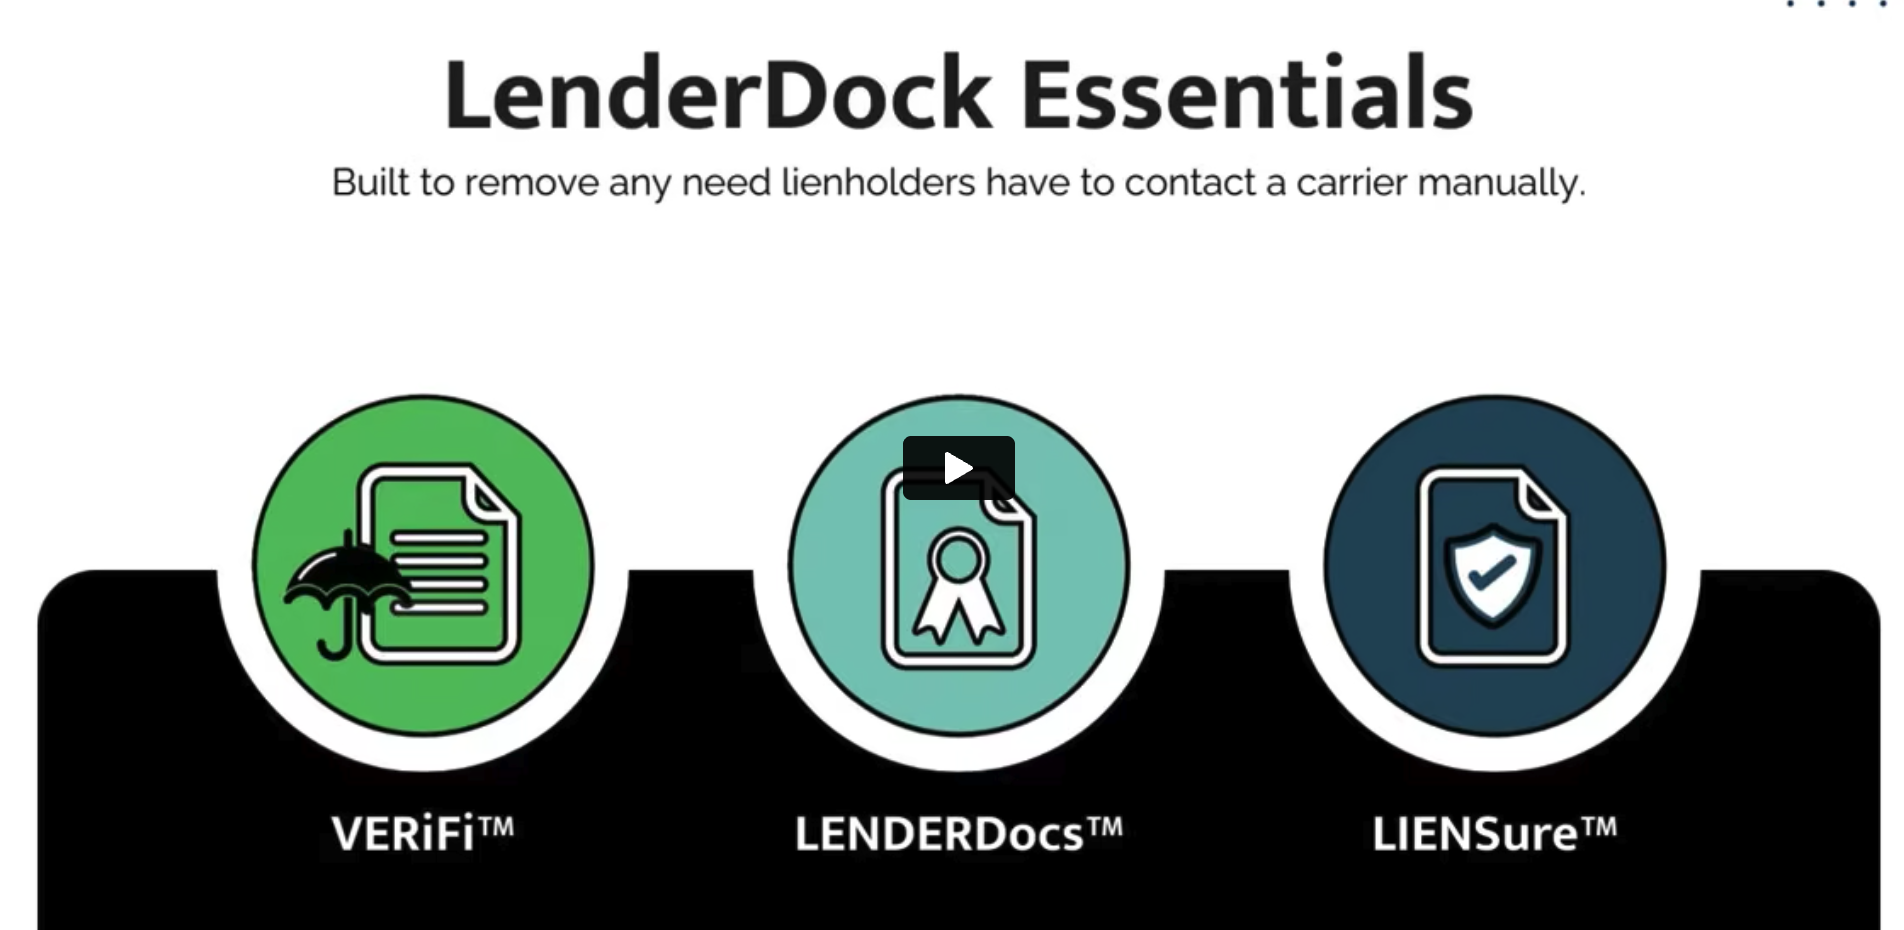
LenderDock provides real-time, insurance policy details through its magical web portal or its APIs.
LIENSure sends corrections digitally, straight from the financial source of truth and in bulk for easy processing.
ESCROWPay verifies what’s actually due before the money moves, then sends the payment and reconciliation data digitally.
NOTiFi delivers required policy, coverage, and billing notices in the formats lienholders actually use
At least check out the genesis of LenderDock Video. It’ll all make sense, the eco-system, that is.
Learn more about our great leadership team and our amazing, people-first, company culture.
There’s a lot going on at LenderDock and in our industries. We threw it all here to make it easier to keep up.
We go to a lot of events and we love to eat. See our calendar of where we’ll be.
New webinars will be coming quite frequently. Educational, success, and sales.
At its core, selling is about meeting customer needs. Utility—the satisfaction a consumer derives from a product—has always been the cornerstone of business success. Today, with countless products flooding the market every second, satisfying those needs has become increasingly challenging.
Millions of companies, each vying for a share of the customer’s wallet, find themselves locked in fierce competition. Over time, businesses realized that success wasn’t just about individual products—it was about creating an integrated network of services that seamlessly address customer needs.
This realization gave rise to ecosystems: dynamic, interconnected systems where businesses collaborate to provide greater value than they could alone.
What is an ecosystem?
An ecosystem is much more than a collection of businesses. It’s an interconnected network of services, platforms, and providers working together to meet customer needs holistically. In an ecosystem, companies collaborate rather than compete—each contributing their unique strengths to create a seamless experience for the end user.
Take the tech sector as an example: Apple’s ecosystem combines hardware, software, apps, and services like iCloud and Apple Pay. Each element enhances the others, creating a unified experience for customers. This builds loyalty and keeps customers within the ecosystem.
The beauty of an ecosystem lies in its ability to anticipate and solve a customer’s broader needs, not just individual transactions. This philosophy is now reshaping industries across the board—including insurance.
Features of Insurance Ecosystems
Insurance, once seen as a standalone product, is transforming into a vital part of broader ecosystems. The shift is driven by the need to meet evolving customer demands while staying competitive in a fast-changing market.
One key feature of insurance ecosystems is the ability to deliver personalized products. Leveraging vast amounts of data and advancements in AI, insurers can now tailor policies to suit individual needs, ensuring coverage that is both relevant and flexible.
For example, a family living in a flood-prone area might receive specialized flood insurance, while an urban renter might get a policy focused on theft protection. By understanding and adapting to the unique circumstances of each customer, insurers create value that goes beyond traditional, one-size-fits-all policies.
Another aspect is the integration of services.
Today’s insurance ecosystems aim to provide a seamless experience, where customers can manage claims, access healthcare, and receive financial advice—all through a single platform. This level of convenience reduces friction and makes it easier for customers to engage with their insurers.
If let’s say a person is injured in a car accident, he could use his insurer’s app to report the incident, schedule a doctor’s appointment, and track repair updates for their vehicle without ever leaving the platform.
Lastly, enhanced risk management. By enabling real-time data sharing among partners, these ecosystems improve the ability to assess and mitigate risks.
Internet of Things (IoT) devices, like sensors in homes or cars, provide insurers with continuous data streams that help identify potential hazards before they become costly claims.
For example, a smart thermostat might alert an insurer to freezing temperatures that could burst pipes, prompting preventative action. This proactive approach not only saves money but also enhances customer satisfaction by preventing losses altogether.
Successful examples of insurance ecosystems
Outlook
As insurance ecosystems continue to evolve, they are expected to integrate even more deeply with emerging technologies like AI, Blockchain, and IoT.
These advancements will streamline processes by enabling automated systems to manage claims and underwriting with minimal human intervention, reducing costs and saving time. They will also improve accessibility by making insurance more inclusive, and offering innovative products like microinsurance to underserved populations.
Ultimately, the future of insurance ecosystems lies in their ability to create value—utility—beyond traditional insurance. By integrating seamlessly into customers’ lives, they will redefine how we think about protection, convenience, and collaboration.
Throughout this transformation, one thing remains certain. Embracing cutting-edge solutions is key to staying ahead. LenderDock simplifies policy verification and lienholder management, empowering insurers and lenders to operate with greater efficiency and accuracy.
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
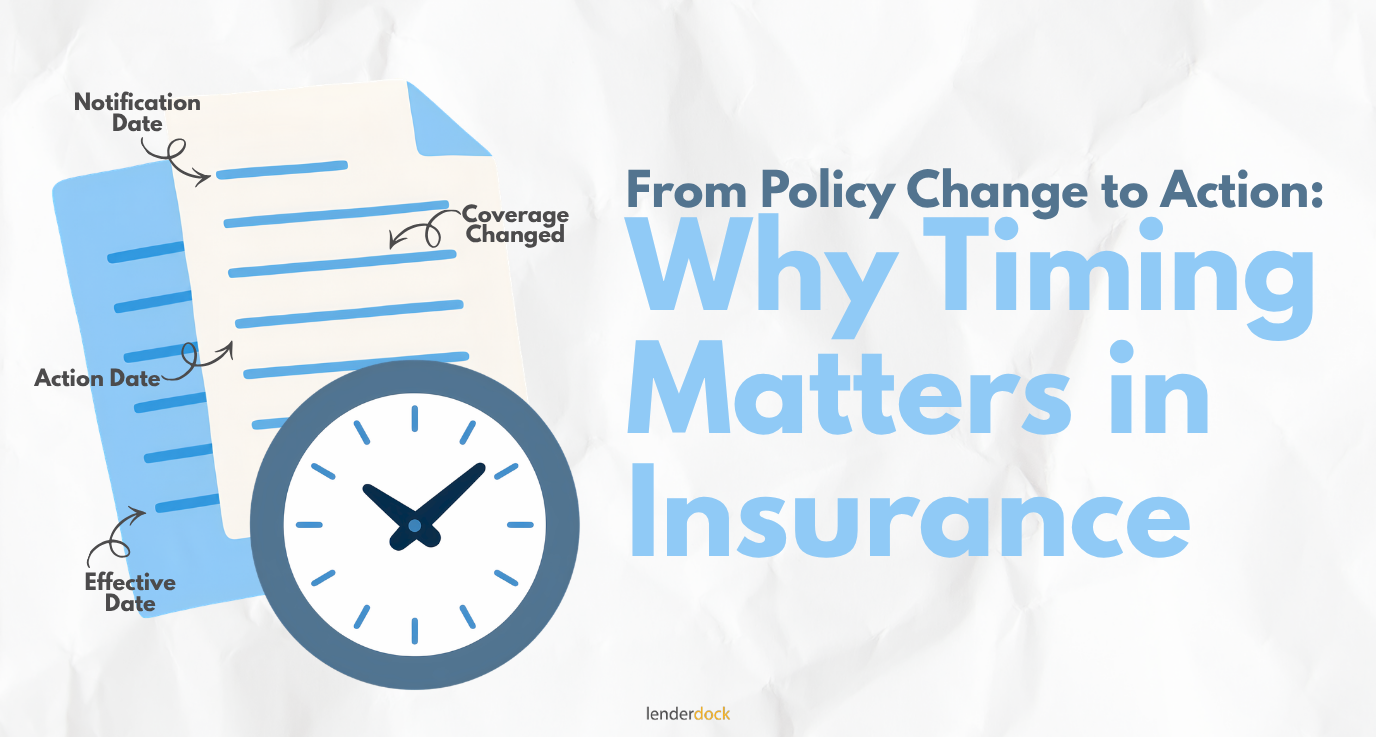
A two-day lag between a policy change and everyone finding out about it used to be annoying, not dangerous. Someone made a call, waited, got an answer, and moved on with their day.
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
Insurance verification is a routine part of the lending and insurance process. A lender needs to know whether a policy is active. A mortgage servicer may need to confirm coverage or mortgagee information. An insurance…
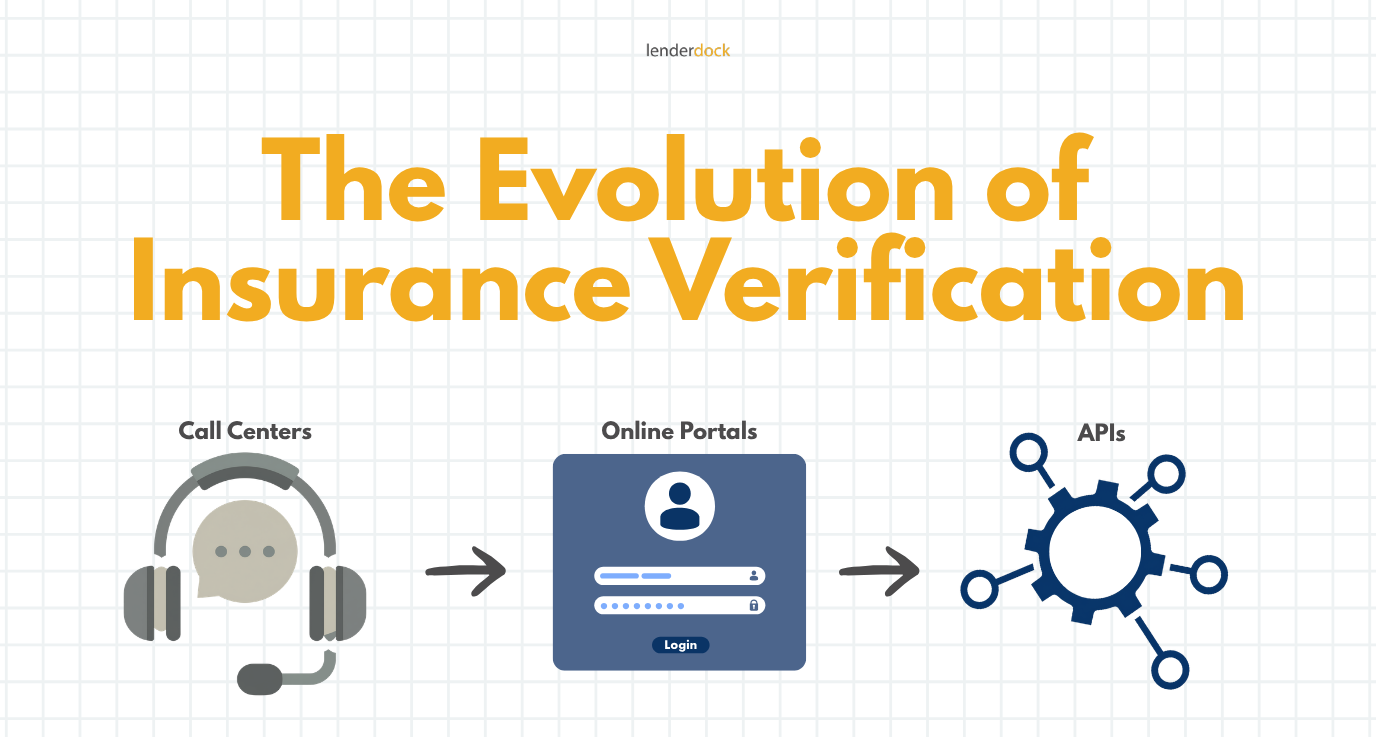
In the earliest version of insurance verification, the person answering the phone actually had to know things. They pulled a physical file, checked handwriting against a ledger, and made a judgment call about whether what…
Two insurers can each have perfectly accurate, well-maintained policy databases and still fail to exchange a single piece of usable data between them.
Every single day, insurance workers face a mountain of simple questions. Are they tired of answering the same questions about policy coverage all day long? Yes, they are. When banks or lenders need to check…
A title company closing a home sale needs to confirm the seller’s policy is active before the deal can move. An auto lender needs the same thing before releasing funds on a car loan. A…
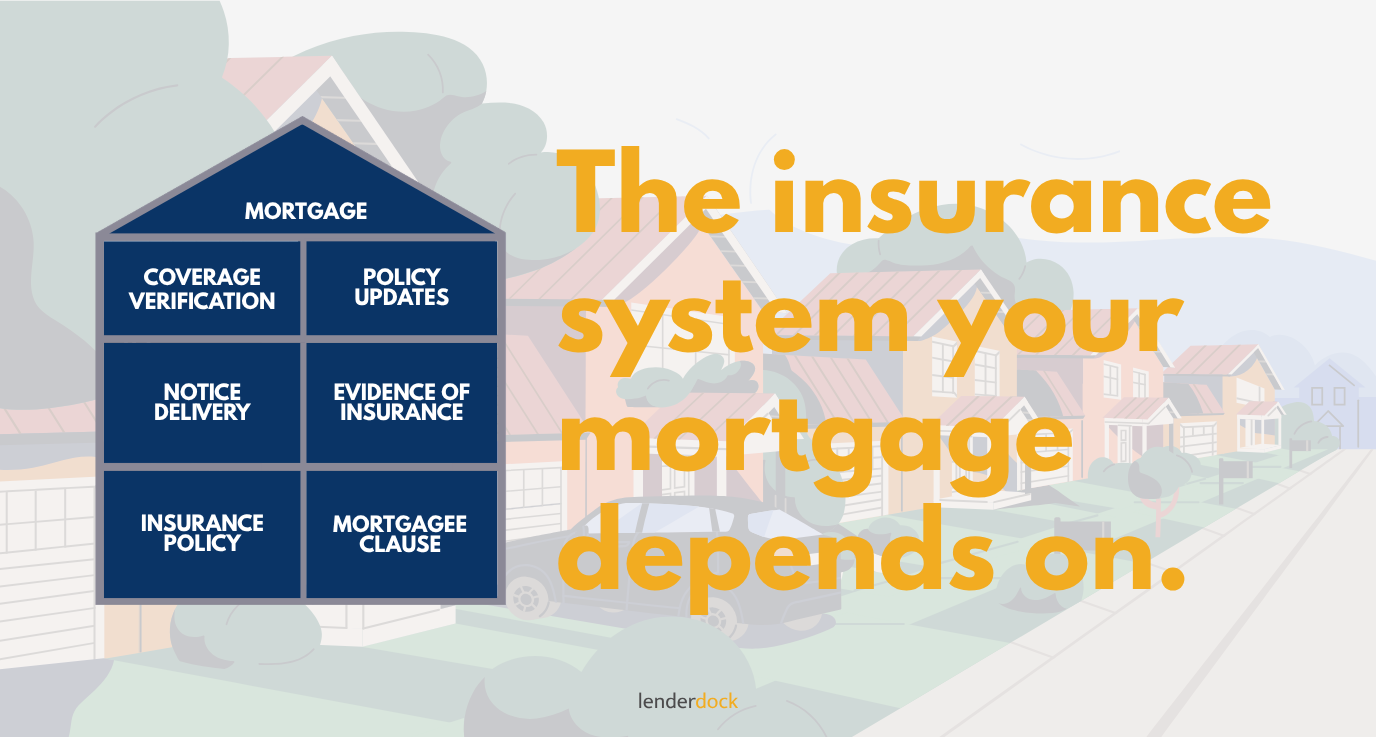
Most people who take out a mortgage never think about insurance as part of the loan itself. It feels adjacent, a separate purchase, something the lender requires but does not really participate in beyond checking…
Mortgagee corrections are a routine part of insurance servicing, but the process behind them is often anything but simple. A lender may find that the mortgagee’s name or address on a policy is out of…
We consectetur adipiscing elit tempor incididunt ut labore. Wondering ipsum dolor sit amet? We consectetur adipiscing ipsum nulla glavrida elit tempor incididunt.