From Policy Change to Action: Why Timing Matters in Insurance
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
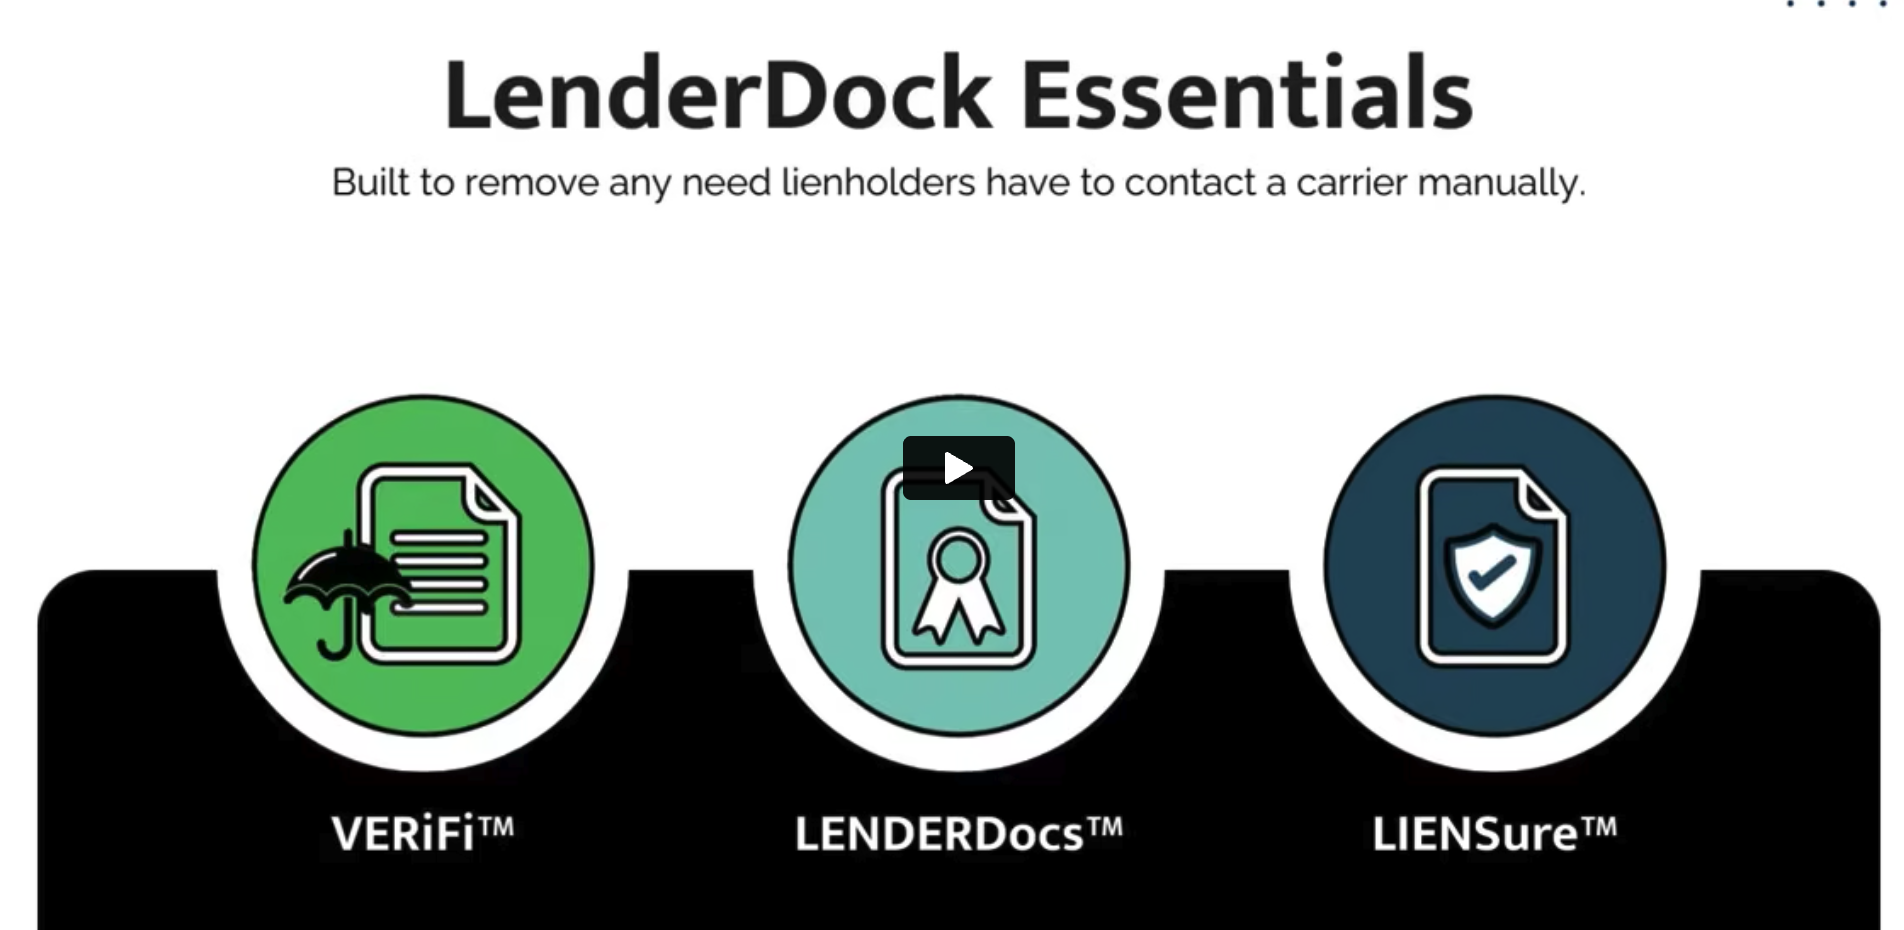
LenderDock provides real-time, insurance policy details through its magical web portal or its APIs.
LIENSure sends corrections digitally, straight from the financial source of truth and in bulk for easy processing.
ESCROWPay verifies what’s actually due before the money moves, then sends the payment and reconciliation data digitally.
NOTiFi delivers required policy, coverage, and billing notices in the formats lienholders actually use
At least check out the genesis of LenderDock Video. It’ll all make sense, the eco-system, that is.
Learn more about our great leadership team and our amazing, people-first, company culture.
There’s a lot going on at LenderDock and in our industries. We threw it all here to make it easier to keep up.
We go to a lot of events and we love to eat. See our calendar of where we’ll be.
New webinars will be coming quite frequently. Educational, success, and sales.
The fate of your property and casualty business is largely dependent on the decisions you make today regarding data utilization.
The insurance sector has been revolutionized by technology, with core processes becoming digitalized and cloud migration increasing. Additionally, insurtech businesses have seen tremendous growth. Through data-driven insights into property risks, a fresh era is on the horizon wherein understanding these risks will be completely changed.
As investors start to recognize the value of companies that collect and analyze innovative data, they have begun differentiating between those enterprises that rely exclusively on traditional data sources and those investing in targeting lucrative niches with sophisticated datasets. The magnitude of these alterations in claims and underwriting management is immense, leaving insurers with a pivotal question: Is your property & casualty data aiding you or hindering you?
As we look ahead to the next decade, it is vital that we ask ourselves: what decisions can I make today to ensure my business’s success in the future? Insurers and consultants agree – by capitalizing on data strategically, you can steer your P&C company towards a prosperous tomorrow. Make mindful choices now about how best to utilize the information for an advantageous outcome ten years from now.
To get an understanding of the dramatic shift in fire risk, consider that insurance firms still use fifty-year-old assumptions when creating their data and models. Furthermore, most systems continue to assess danger and charge premiums dependent on property or company ZIP codes from over four decades ago!
With the emergence of modern technology, we can now assess over a thousand various risk factors for each property across America – from updated aerial imagery to geospatial information that is more accurate and thorough than ever before. This surpasses traditional underwriters who are limited in evaluating only a few data points on each home or business regardless of whether two residences in the same ZIP code may have extremely contrasting levels of wildfire, flood, and crime danger.
Despite gaining access to hundreds of data points, insurance companies often neglect the majority of them. For example, lightning damage is an expensive claim category that contains a wealth of risk-related information, but many insurers hardly consider it when assessing properties. In addition to this oversight, 30% of traditional systems fail to consider the location and distance from their nearest fire station – something critical for accurately estimating possible fire damage.
When the data you possess is inadequate or flawed, taking risks without caution can be disastrous. Consequently, investing in risk models and analytics will prove fruitless if there are doubts about your information’s accuracy. In such cases, it pays to exercise extreme care when making decisions as even small mistakes could have major implications.
In the last few years, access to excellent property and casualty data has rocketed; it is now easier than ever for companies’ underwriters to receive real-time information through cloud storage options and API accessibility. Businesses are looking forward to obtaining cost-effective up-to-date data without difficulty or hassle.
With dozens of businesses and thousands of data points to draw from, you can greatly expand your knowledge about properties, customers, and potential risks. By having access to unparalleled data points, you can drastically improve your understanding of risk and pricing. With just a few clicks, you can easily find out the distance to fire stations and hydrants in your area, if there are any underground storage tanks on-site, the nearest PFA sites or Superfund sites nearby, as well as have direct access to building permits.
Today, the insurance industry is slowly but surely starting to adopt new technologies that involve data analytics. With personal and commercial lines of business becoming commoditized, executives have begun relying on data analysis in order to increase their profits and gain a competitive advantage over other companies. Consequently, innovative data has become an indispensable asset for them.
Currently, data is more readily available than ever before – all while costing much less money.
P&C insurance companies in Europe and the United States are heavily investing in data analytics to ensure that every element of their operations is optimized: from risk selection and pricing, and application profiles, all the way up to underwriting. By doing so, they can give priority to providing better customer service while also achieving greater success overall.
A recent McKinsey study uncovered that the leading insurance companies have exhibited immense success by utilizing data and improved analytics in underwriting. These front-runners are experiencing a significant three to five-point drop in loss ratios, a 10%-15% rise in new business premiums, and a 5%-10% increase in retention rates. Superiority in underwriting, as well as pricing knowledge, evidently separates these industry champions from their competition.
McKinsey’s report proclaims that external data is the main catalyst in driving analytics value. By using sophisticated data and analytics technology, insurers can gain valuable insight into potential risks while simultaneously improving their overall insurance process – from profile applications to risk selection and pricing. Organizations at the vanguard of progress are now focusing on small improvements across various areas such as:
Assessing Risk: By leveraging both internal and external data sources, insurers can refine their risk selection process to determine which applicants are good risks and avoid those that may have a higher likelihood of causing economic losses. While it is not possible to entirely eliminate losses, utilizing data analytics for smarter decision-making will help identify and prevent highly probable ones.
Prefill: When you utilize the correct next-generation data, it can greatly improve and streamline your customer journey. In particular, the screening and interview process becomes far less laborious; with integrated next-gen data systems, you can quickly match and pre-fill necessary information for clients or customers at an inexpensive price point. Fewer questions in interviews speed up the sales cycle while maintaining a smooth experience – thus maximizing efficiency along their journey!
Cost: By swiftly accessing and incorporating the appropriate internal data, combined with analyzing a broad range of external information, insurers are better equipped to present compelling arguments for their pricing structure to regulators. Plus, they can accurately price policies that reflect an honest assessment of risk. Compared to state-of-the-art systems, property owners in zip codes with an F wildfire rating – such as a home situated close to wild areas with dry brush near the premises – and those living in low-risk districts both pay almost identical premiums. Consequently, customers who are exposed to higher levels of fire danger should be paying more than others that don’t face the same risks.
Promotion: As one of the few areas in insurance that have yet to be fully explored, marketing presents itself as a ripe area for insurers – from small to medium-sized businesses – looking for an advantage over their competitors. By leveraging advanced data and analytics, these companies can position themselves at the forefront of risk selection through smarter and more targeted outreach techniques. When done right, this process yields stronger leads with less risk potential which often results in increased profitability.
It is essential to remember that data is a dynamic element, continually growing and changing.
By utilizing both your own internal data and precision external data, you can gain tremendous value during the insurance underwriting process. This combination allows you to explore more property risk information than ever before.
The market is, at last, recognizing the capabilities of this groundbreaking technology, initiating a new trend that necessitates you to stay in first place for your business to remain competitive. With expanded access to property risk data and analytics, those who innovate initially will emerge from their competitors. Get ahead now or be left behind – make sure your business takes advantage of these opportunities as soon as possible!
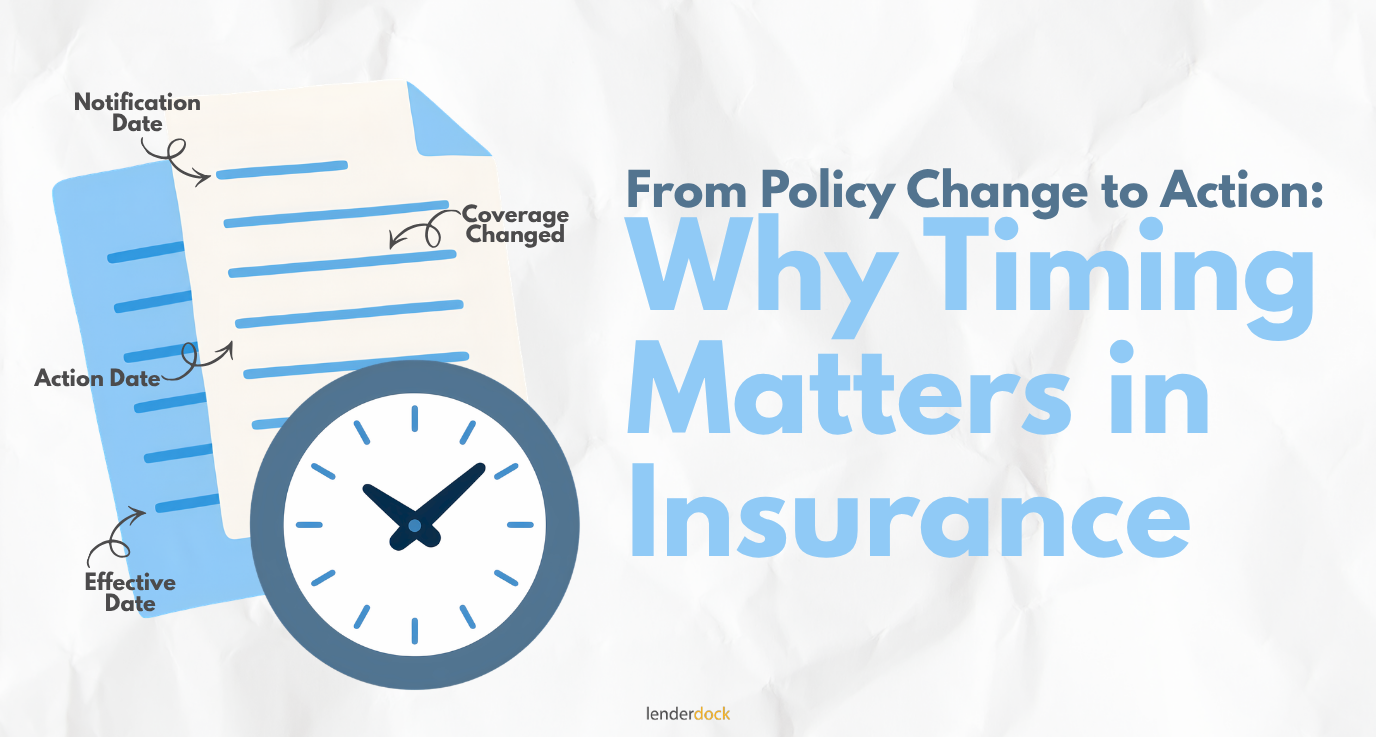
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
A two-day lag between a policy change and everyone finding out about it used to be annoying, not dangerous. Someone made a call, waited, got an answer, and moved on with their day.
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
Insurance verification is a routine part of the lending and insurance process. A lender needs to know whether a policy is active. A mortgage servicer may need to confirm coverage or mortgagee information. An insurance…
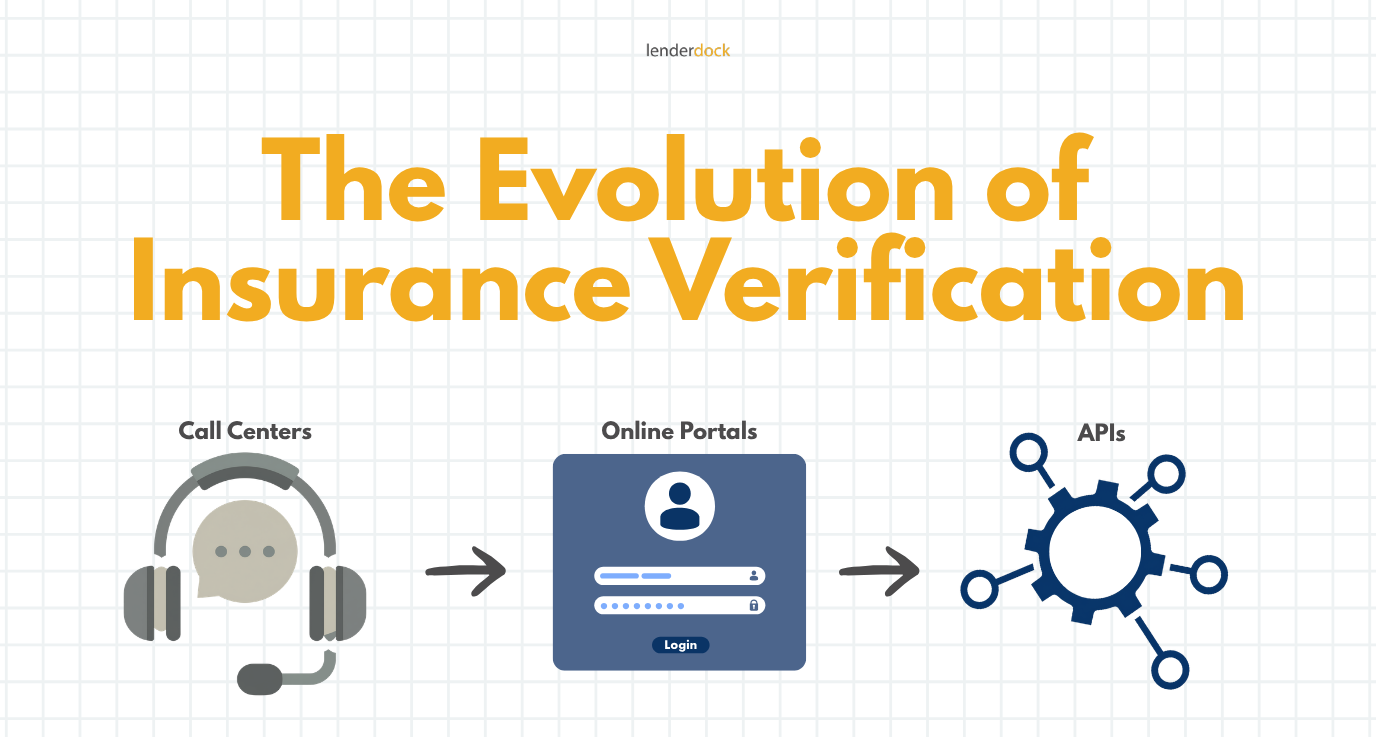
In the earliest version of insurance verification, the person answering the phone actually had to know things. They pulled a physical file, checked handwriting against a ledger, and made a judgment call about whether what…
Two insurers can each have perfectly accurate, well-maintained policy databases and still fail to exchange a single piece of usable data between them.
Every single day, insurance workers face a mountain of simple questions. Are they tired of answering the same questions about policy coverage all day long? Yes, they are. When banks or lenders need to check…
A title company closing a home sale needs to confirm the seller’s policy is active before the deal can move. An auto lender needs the same thing before releasing funds on a car loan. A…
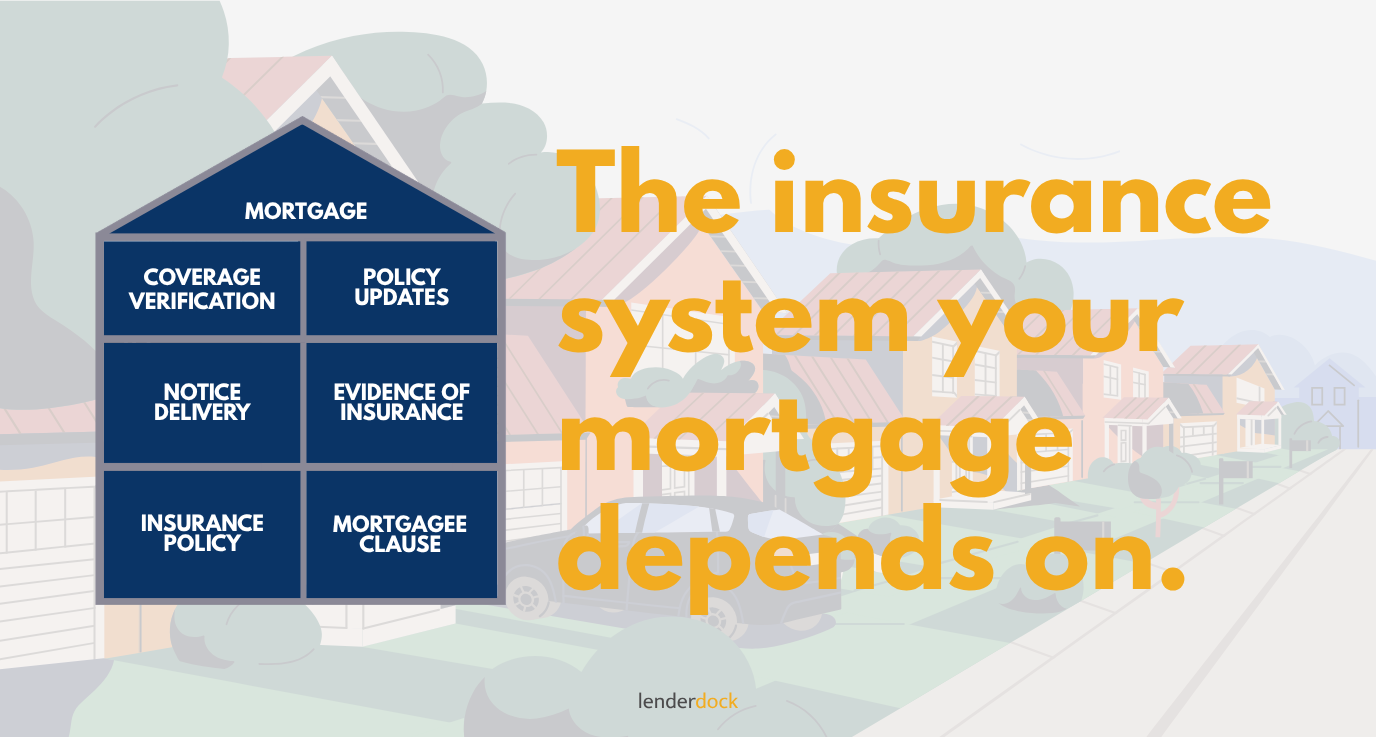
Most people who take out a mortgage never think about insurance as part of the loan itself. It feels adjacent, a separate purchase, something the lender requires but does not really participate in beyond checking…
Mortgagee corrections are a routine part of insurance servicing, but the process behind them is often anything but simple. A lender may find that the mortgagee’s name or address on a policy is out of…
We consectetur adipiscing elit tempor incididunt ut labore. Wondering ipsum dolor sit amet? We consectetur adipiscing ipsum nulla glavrida elit tempor incididunt.