From Policy Change to Action: Why Timing Matters in Insurance
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
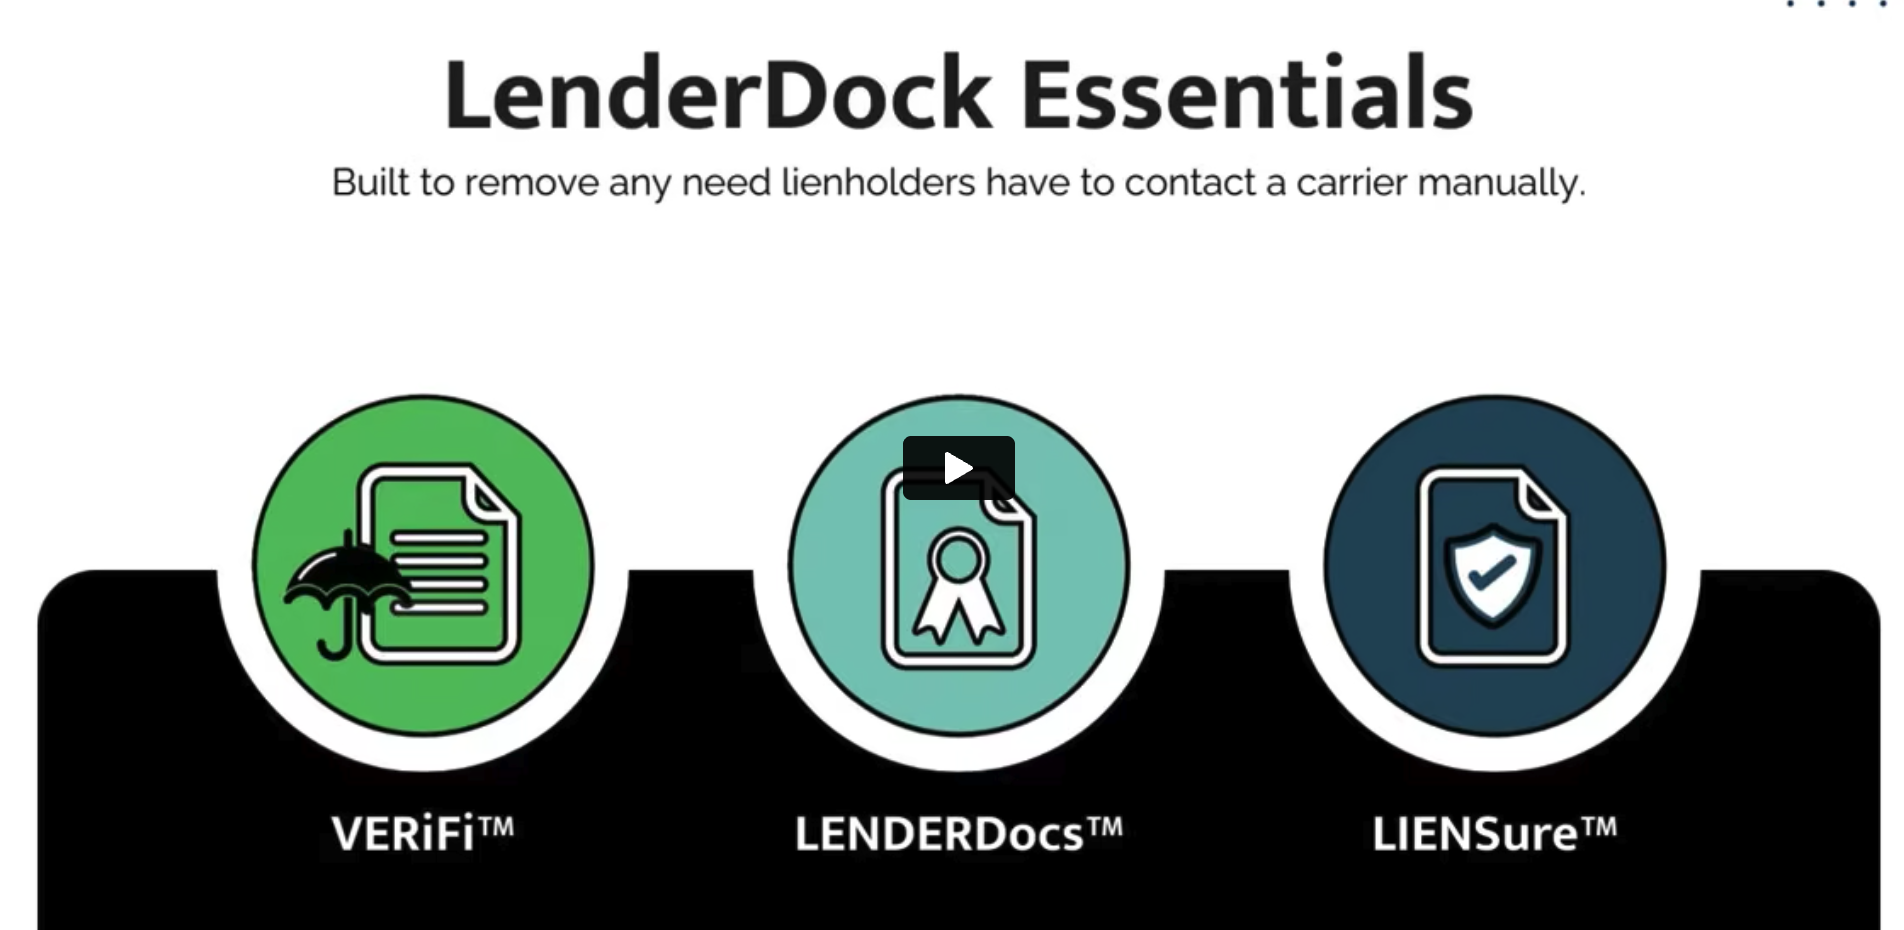
LenderDock provides real-time, insurance policy details through its magical web portal or its APIs.
LIENSure sends corrections digitally, straight from the financial source of truth and in bulk for easy processing.
ESCROWPay verifies what’s actually due before the money moves, then sends the payment and reconciliation data digitally.
NOTiFi delivers required policy, coverage, and billing notices in the formats lienholders actually use
At least check out the genesis of LenderDock Video. It’ll all make sense, the eco-system, that is.
Learn more about our great leadership team and our amazing, people-first, company culture.
There’s a lot going on at LenderDock and in our industries. We threw it all here to make it easier to keep up.
We go to a lot of events and we love to eat. See our calendar of where we’ll be.
New webinars will be coming quite frequently. Educational, success, and sales.
In today’s data-driven world, businesses across various sectors are harnessing the power of data analysis to make informed decisions, drive efficiencies, and unlock new opportunities. Among these industries, the insurance sector stands out as a prime example of how data analysis is reshaping operations, mitigating risks, and enhancing customer experiences.
The insurance industry is inherently data-rich, with vast amounts of information collected through policy applications, claims processing, underwriting, and customer interactions. This wealth of data encompasses demographic details, risk factors, claim histories, and more. Analyzing this data provides insurers with invaluable insights into market trends, customer behaviors, and emerging risks.
One of the key applications of data analysis in the insurance sector is predictive modeling. By leveraging historical data and advanced analytical techniques such as machine learning, insurers can assess risk more accurately. Predictive models help identify patterns and predict the likelihood of future events, enabling insurers to price policies effectively and optimize underwriting decisions.
Fraudulent claims pose a significant challenge for insurers, leading to financial losses and reputational damage. Data analysis plays a crucial role in detecting and preventing insurance fraud. By analyzing various data points such as claim histories, transaction patterns, and behavioral anomalies, insurers can flag suspicious activities and investigate them further, ultimately reducing fraudulent losses.
Data analysis empowers insurers to move away from traditional one-size-fits-all pricing models towards more personalized approaches. By analyzing customer data, including demographics, lifestyle choices, and previous interactions, insurers can tailor pricing and coverage options to individual needs. Additionally, data analysis provides valuable insights into customer preferences, enabling insurers to enhance their products and services accordingly.
Conclusion
In conclusion, data analysis is revolutionizing the insurance industry, driving innovation, and transforming traditional business practices. By harnessing the power of data, insurers can better understand their customers, manage risks effectively, and improve operational efficiency. As the industry continues to evolve, data analysis will remain a cornerstone of success, enabling insurers to thrive in an increasingly competitive landscape.
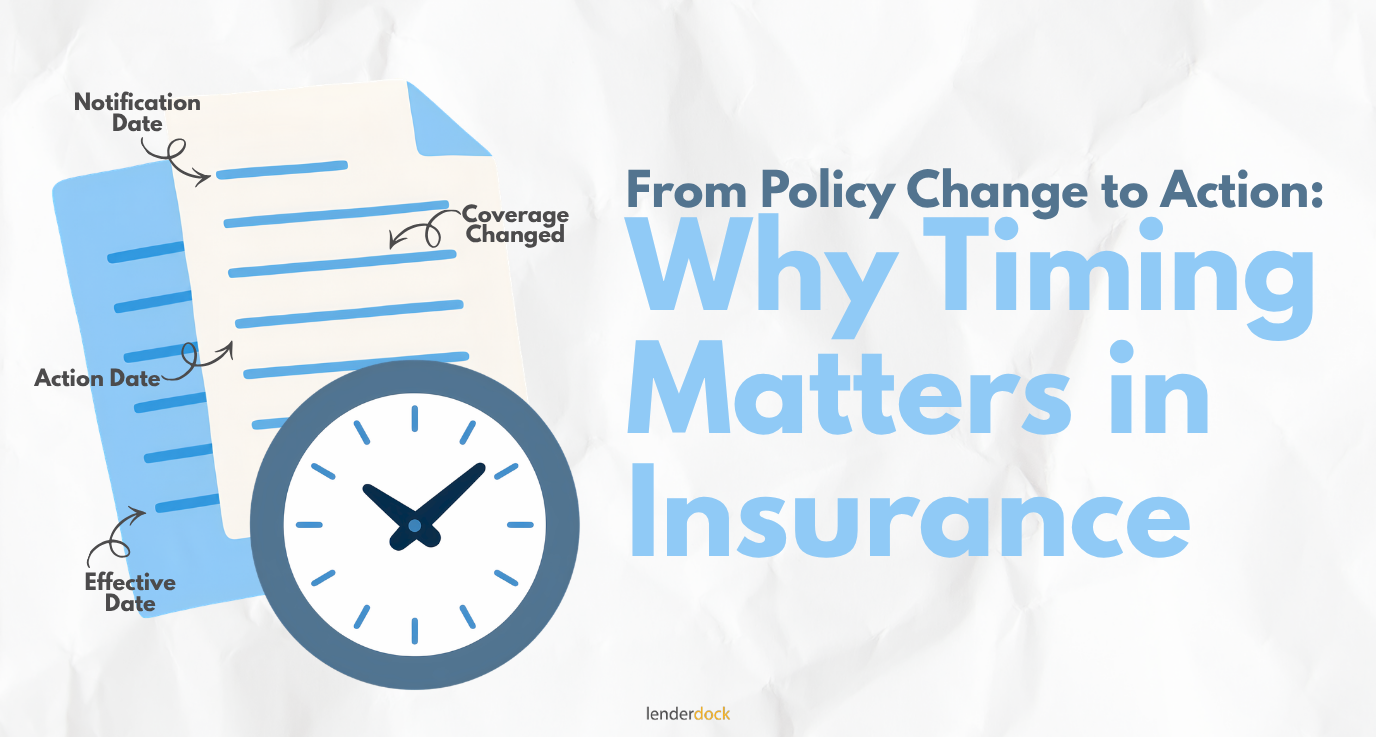
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
A two-day lag between a policy change and everyone finding out about it used to be annoying, not dangerous. Someone made a call, waited, got an answer, and moved on with their day.
We’ve heard people in mortgage servicing use verification and tracking as if they’re interchangeable, and honestly, for a lot of daily work, treating them that way doesn’t break anything.
Insurance verification is a routine part of the lending and insurance process. A lender needs to know whether a policy is active. A mortgage servicer may need to confirm coverage or mortgagee information. An insurance…
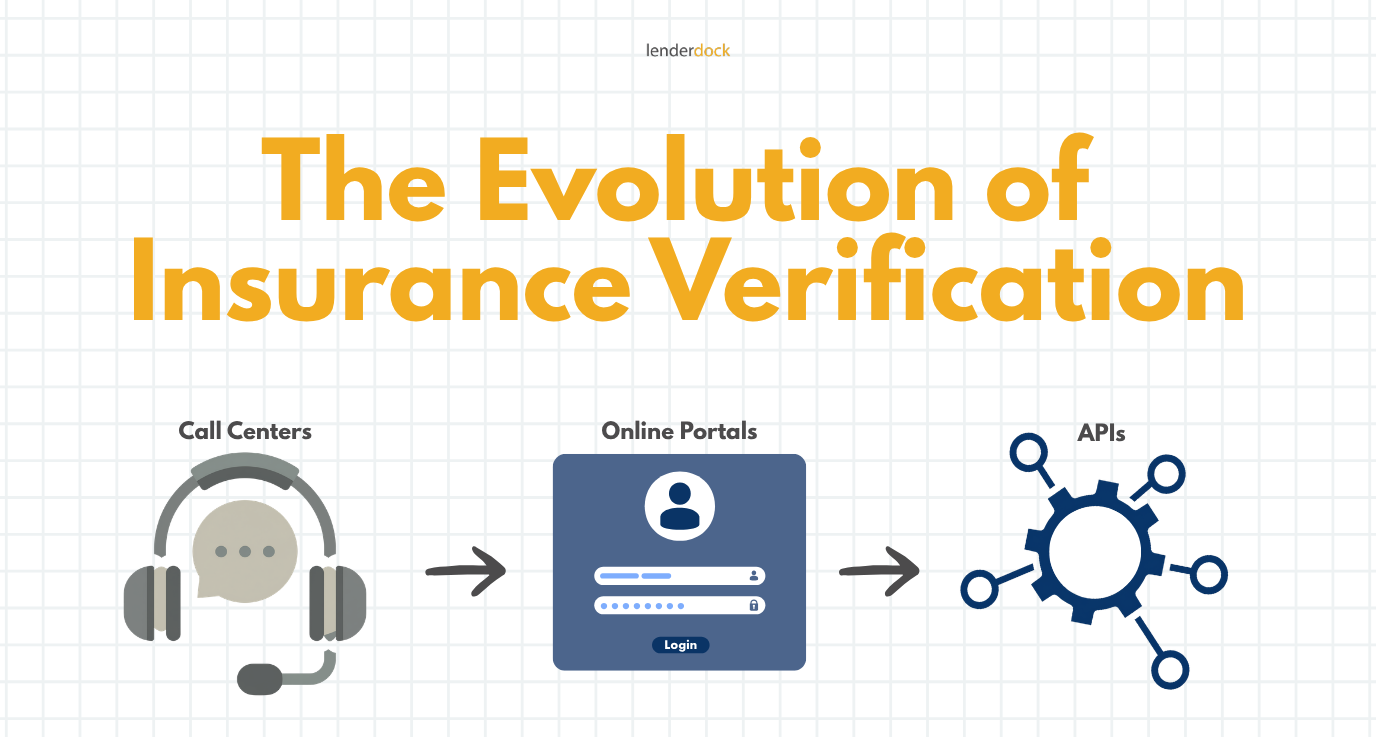
In the earliest version of insurance verification, the person answering the phone actually had to know things. They pulled a physical file, checked handwriting against a ledger, and made a judgment call about whether what…
Two insurers can each have perfectly accurate, well-maintained policy databases and still fail to exchange a single piece of usable data between them.
Every single day, insurance workers face a mountain of simple questions. Are they tired of answering the same questions about policy coverage all day long? Yes, they are. When banks or lenders need to check…
A title company closing a home sale needs to confirm the seller’s policy is active before the deal can move. An auto lender needs the same thing before releasing funds on a car loan. A…
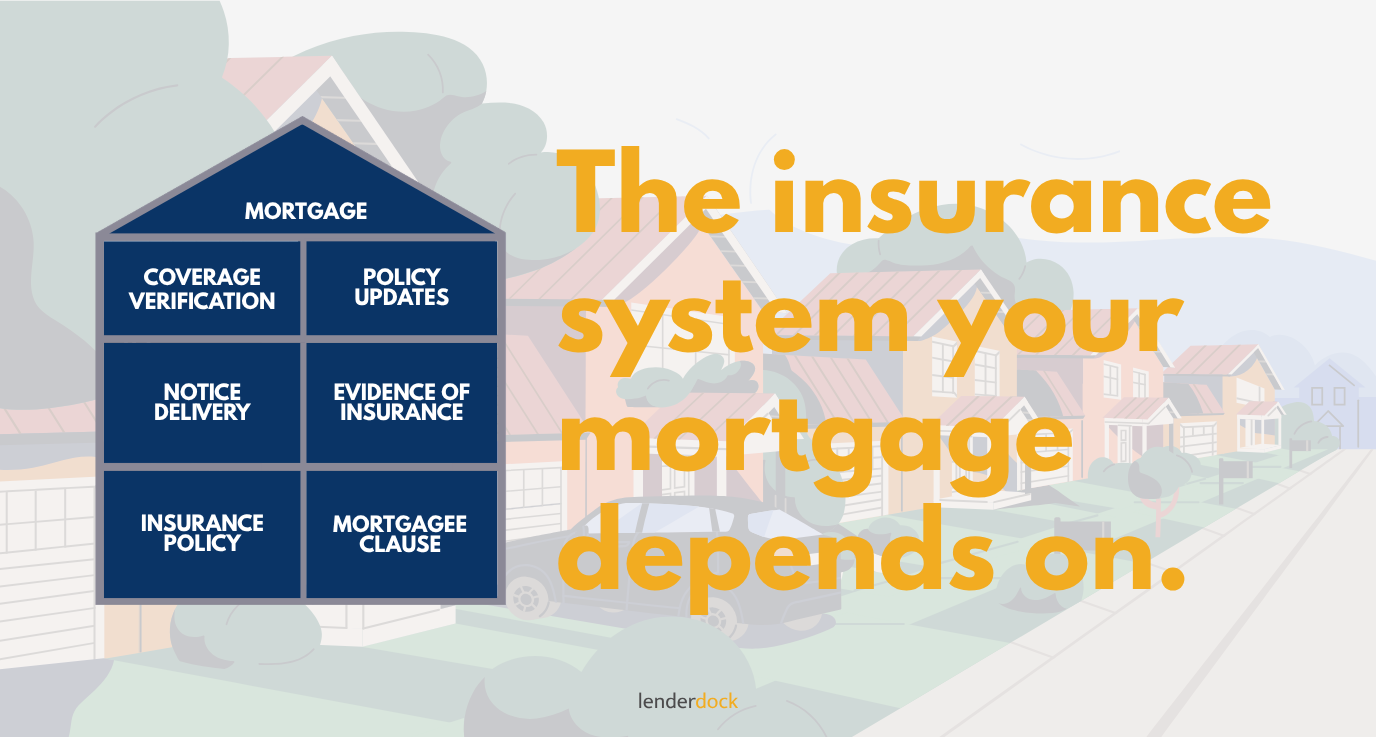
Most people who take out a mortgage never think about insurance as part of the loan itself. It feels adjacent, a separate purchase, something the lender requires but does not really participate in beyond checking…
Mortgagee corrections are a routine part of insurance servicing, but the process behind them is often anything but simple. A lender may find that the mortgagee’s name or address on a policy is out of…
We consectetur adipiscing elit tempor incididunt ut labore. Wondering ipsum dolor sit amet? We consectetur adipiscing ipsum nulla glavrida elit tempor incididunt.